The headline above seems ridiculous when gas prices are almost $4.50/gallon and diesel is at a record $6.52/gallon (nationwide averages). Inflation is running hot across the board, from electronics to pet care to lawn care. Surely consumers are struggling. But there are two ways higher gas prices can play out:
- Consumers pay up for higher gas prices and cut back everywhere else, or
- Consumers pay up for higher gas prices and continue buying everything else at the same pace (never mind inflation)
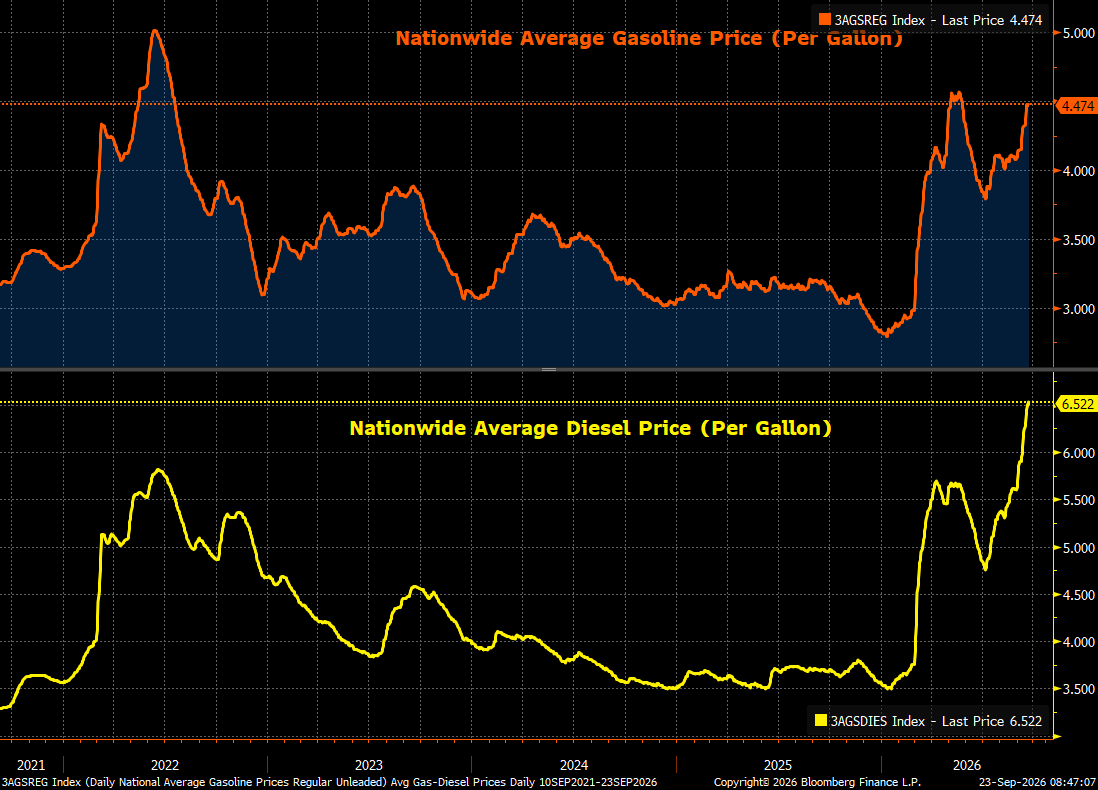
This has implications for Fed rate hikes and long-term rates. In the first scenario, hikes slow the economy further. Higher rates cannot produce more oil, but it can lower demand everywhere else. Longer-term yields are likely to fall.
In the second, hiking may simply be “meeting the moment” of stronger nominal demand, keeping long-term yields elevated. If the Fed eventually slams the brakes, growth and long-term yields would fall.
Stay on Top of Market Trends
The Carson Investment Research newsletter offers up-to-date market news, analysis and insights. Subscribe today!
"*" indicates required fields
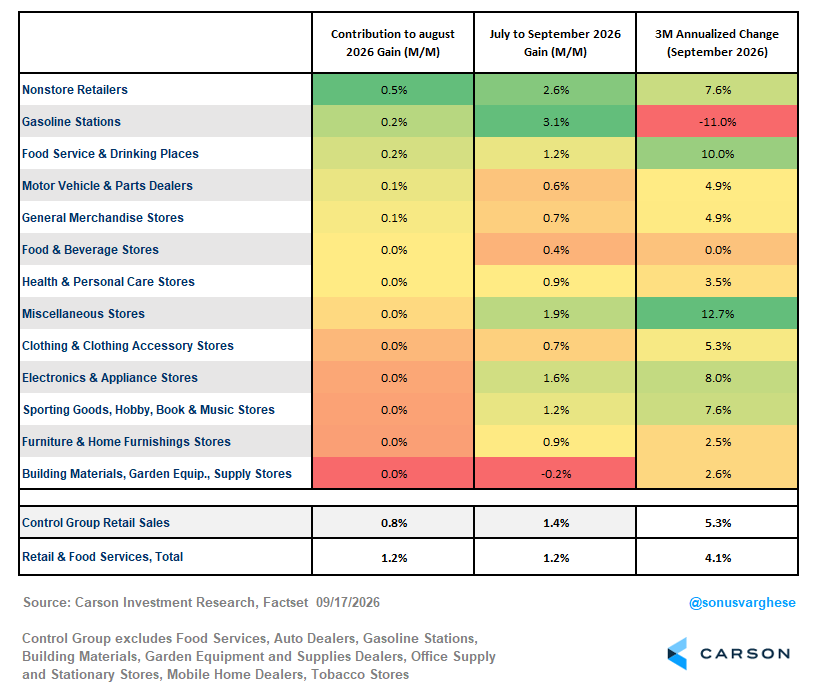
It’s clear we’re in the second dynamic now, especially after August retail sales showed spending running hot. Sales rose 1.2% over the month, but monthly data are volatile, so we look at the last three months. Sales increased at a 4.1% annualized pace between June and August, while core retail sales (excluding gas stations and autos) rose at a stronger 5.3% pace. Notably:
- Online spending (“nonstore retailers”) rose 7.6% annualized
- Restaurant sales (“food services and drinking places”) rose 10%
Restaurant sales are amongst the most discretionary line items—the first thing households cut when genuinely stretched. They haven’t. These are nominal figures, so prices are doing some lifting. But even after adjusting for inflation, restaurant sales are up over 6%. Households are willing to pay higher prices and increase spending volume, which is telling.
The recent jobs report also pointed to a solid and improving labor market, and jobless claims underline this. On a non-seasonally adjusted basis, initial claims are 22% below the comparable week a year ago and at their lowest since September 2022. Claims are also 12% below the 2018-2019 benchmark for this week, consistent with a healthy labor market. Layoffs remain historically low. The insured unemployment rate (which is continuing jobless claims as a percent of the workforce) is at 1.0%, matching the 2018-2019 average and below 1.2% a year ago.
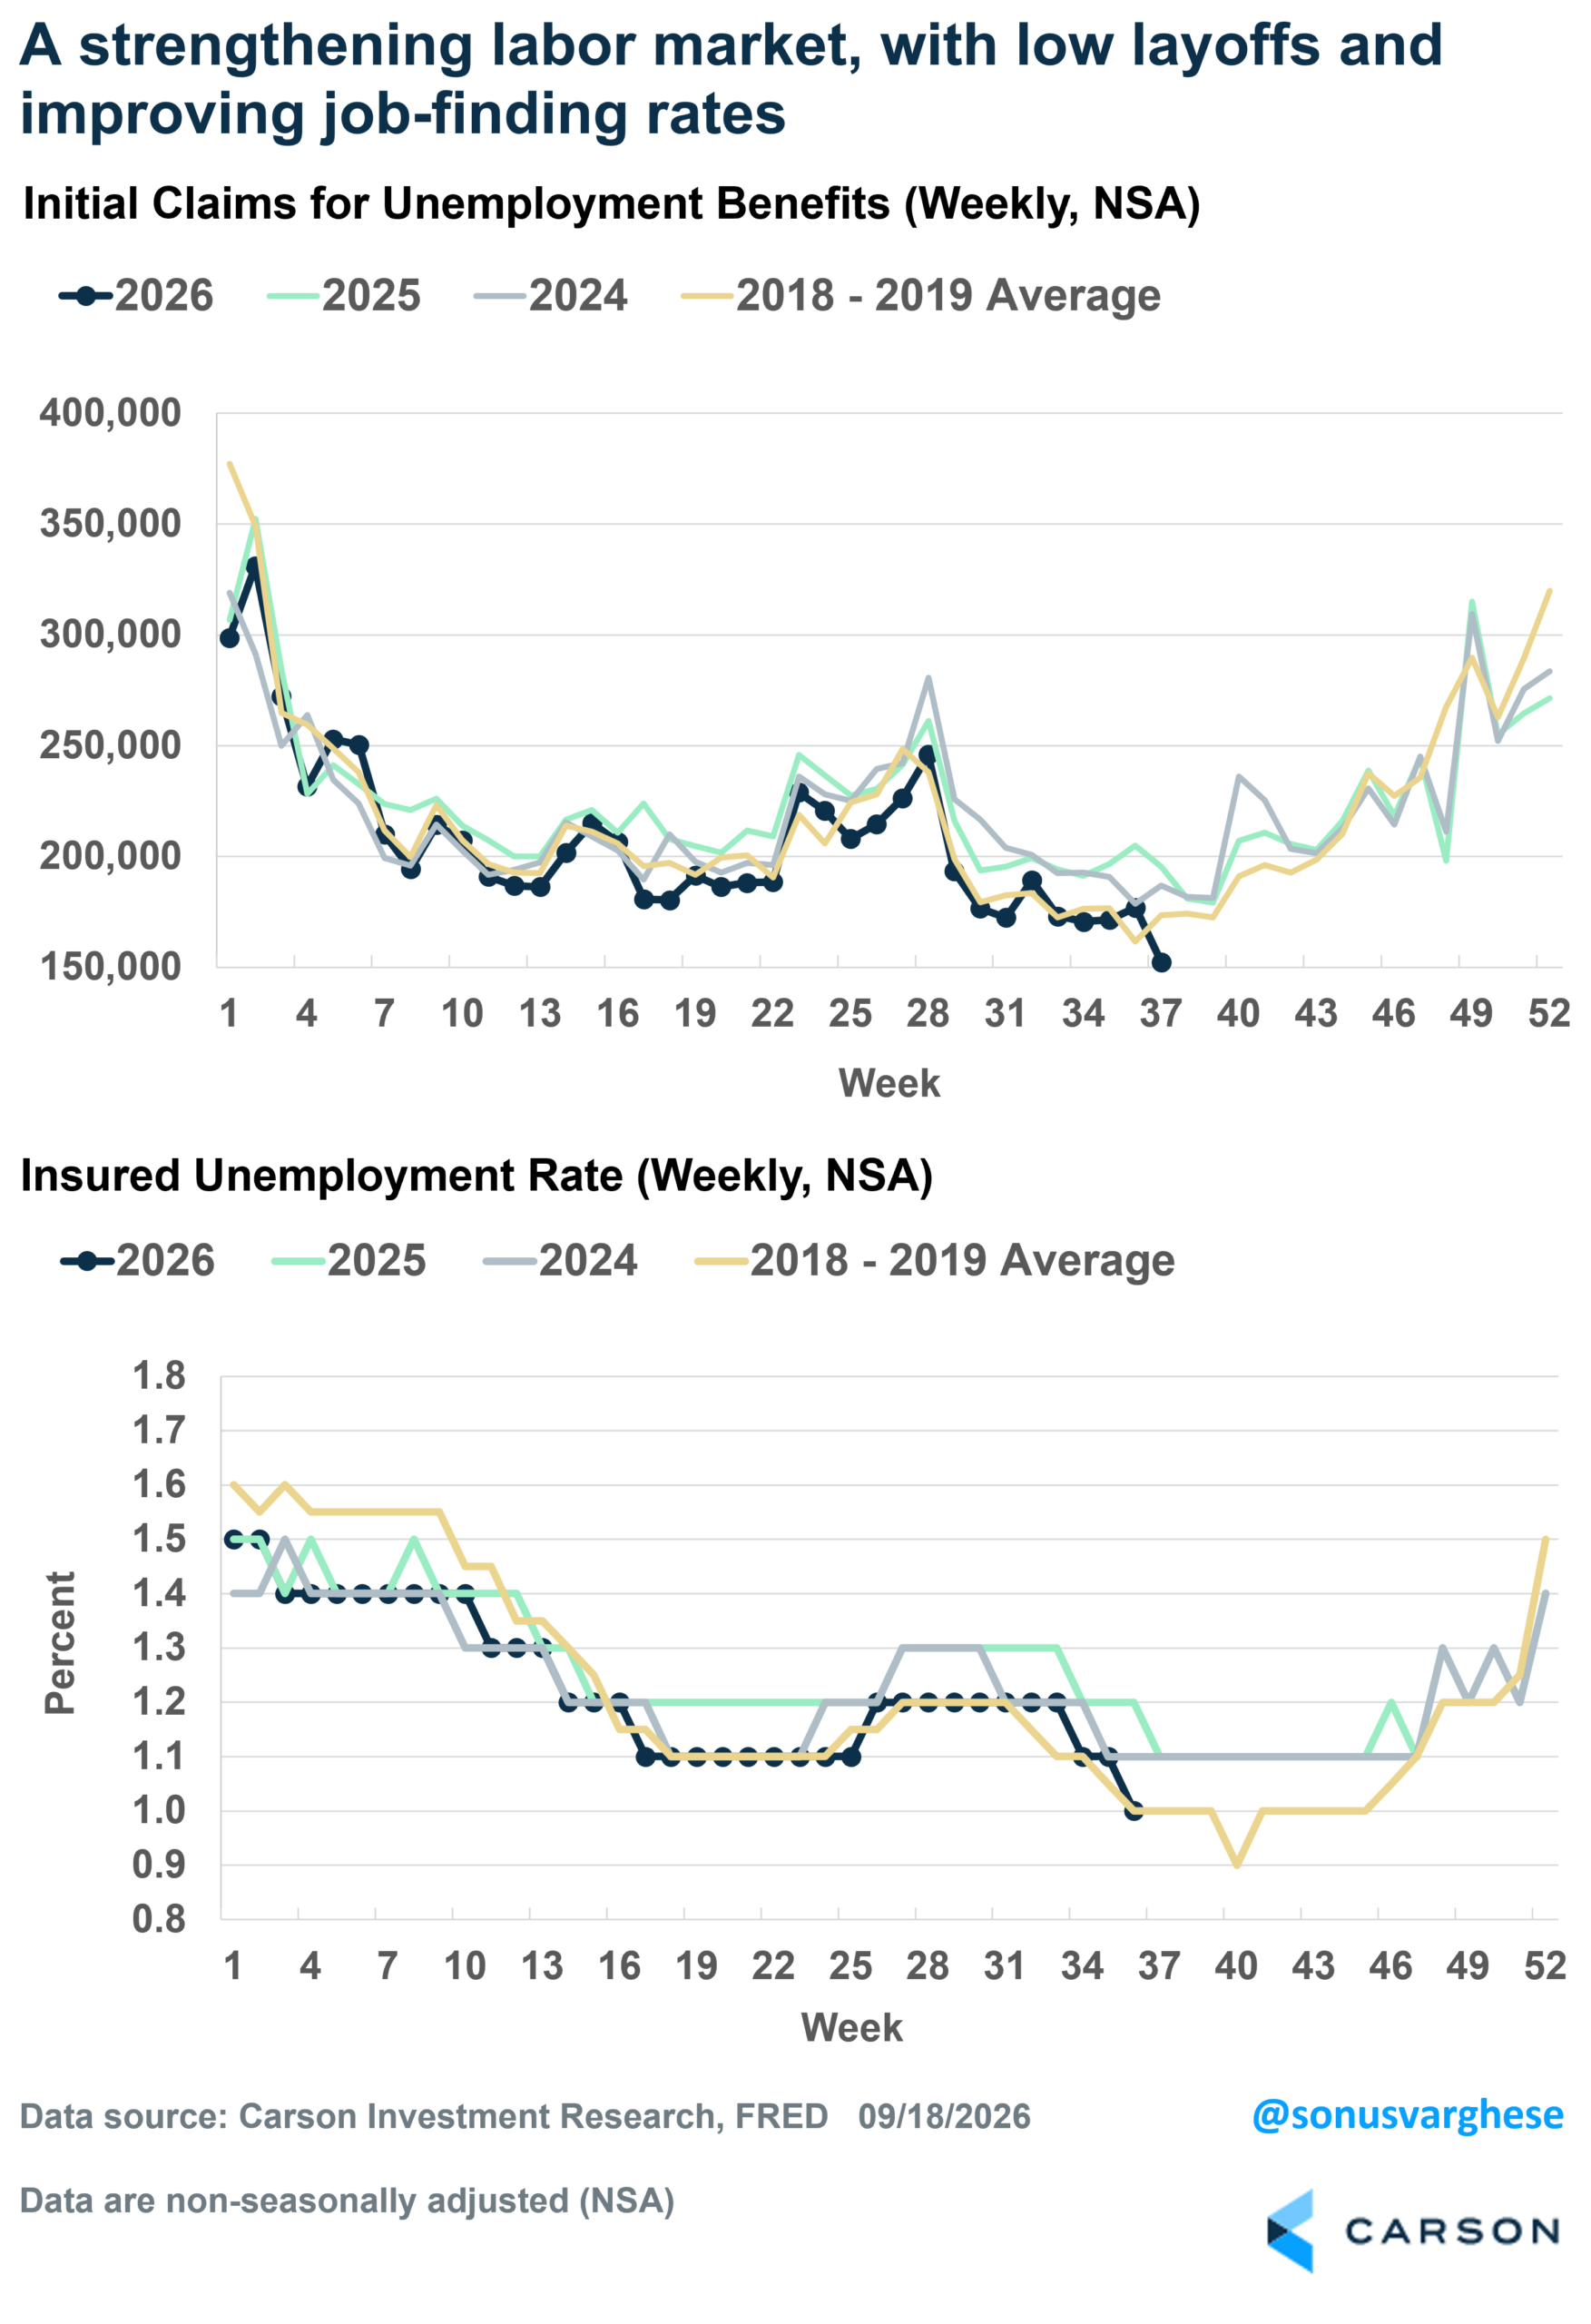
Nothing points to labor market deterioration, and lower continuing claims point to a better labor market for the unemployed. Put that next to retail sales, and you get the same message: the consumer is in a strong place, despite inflation.
Households’ Balance Sheets Are Strong, Bolstered by Stocks
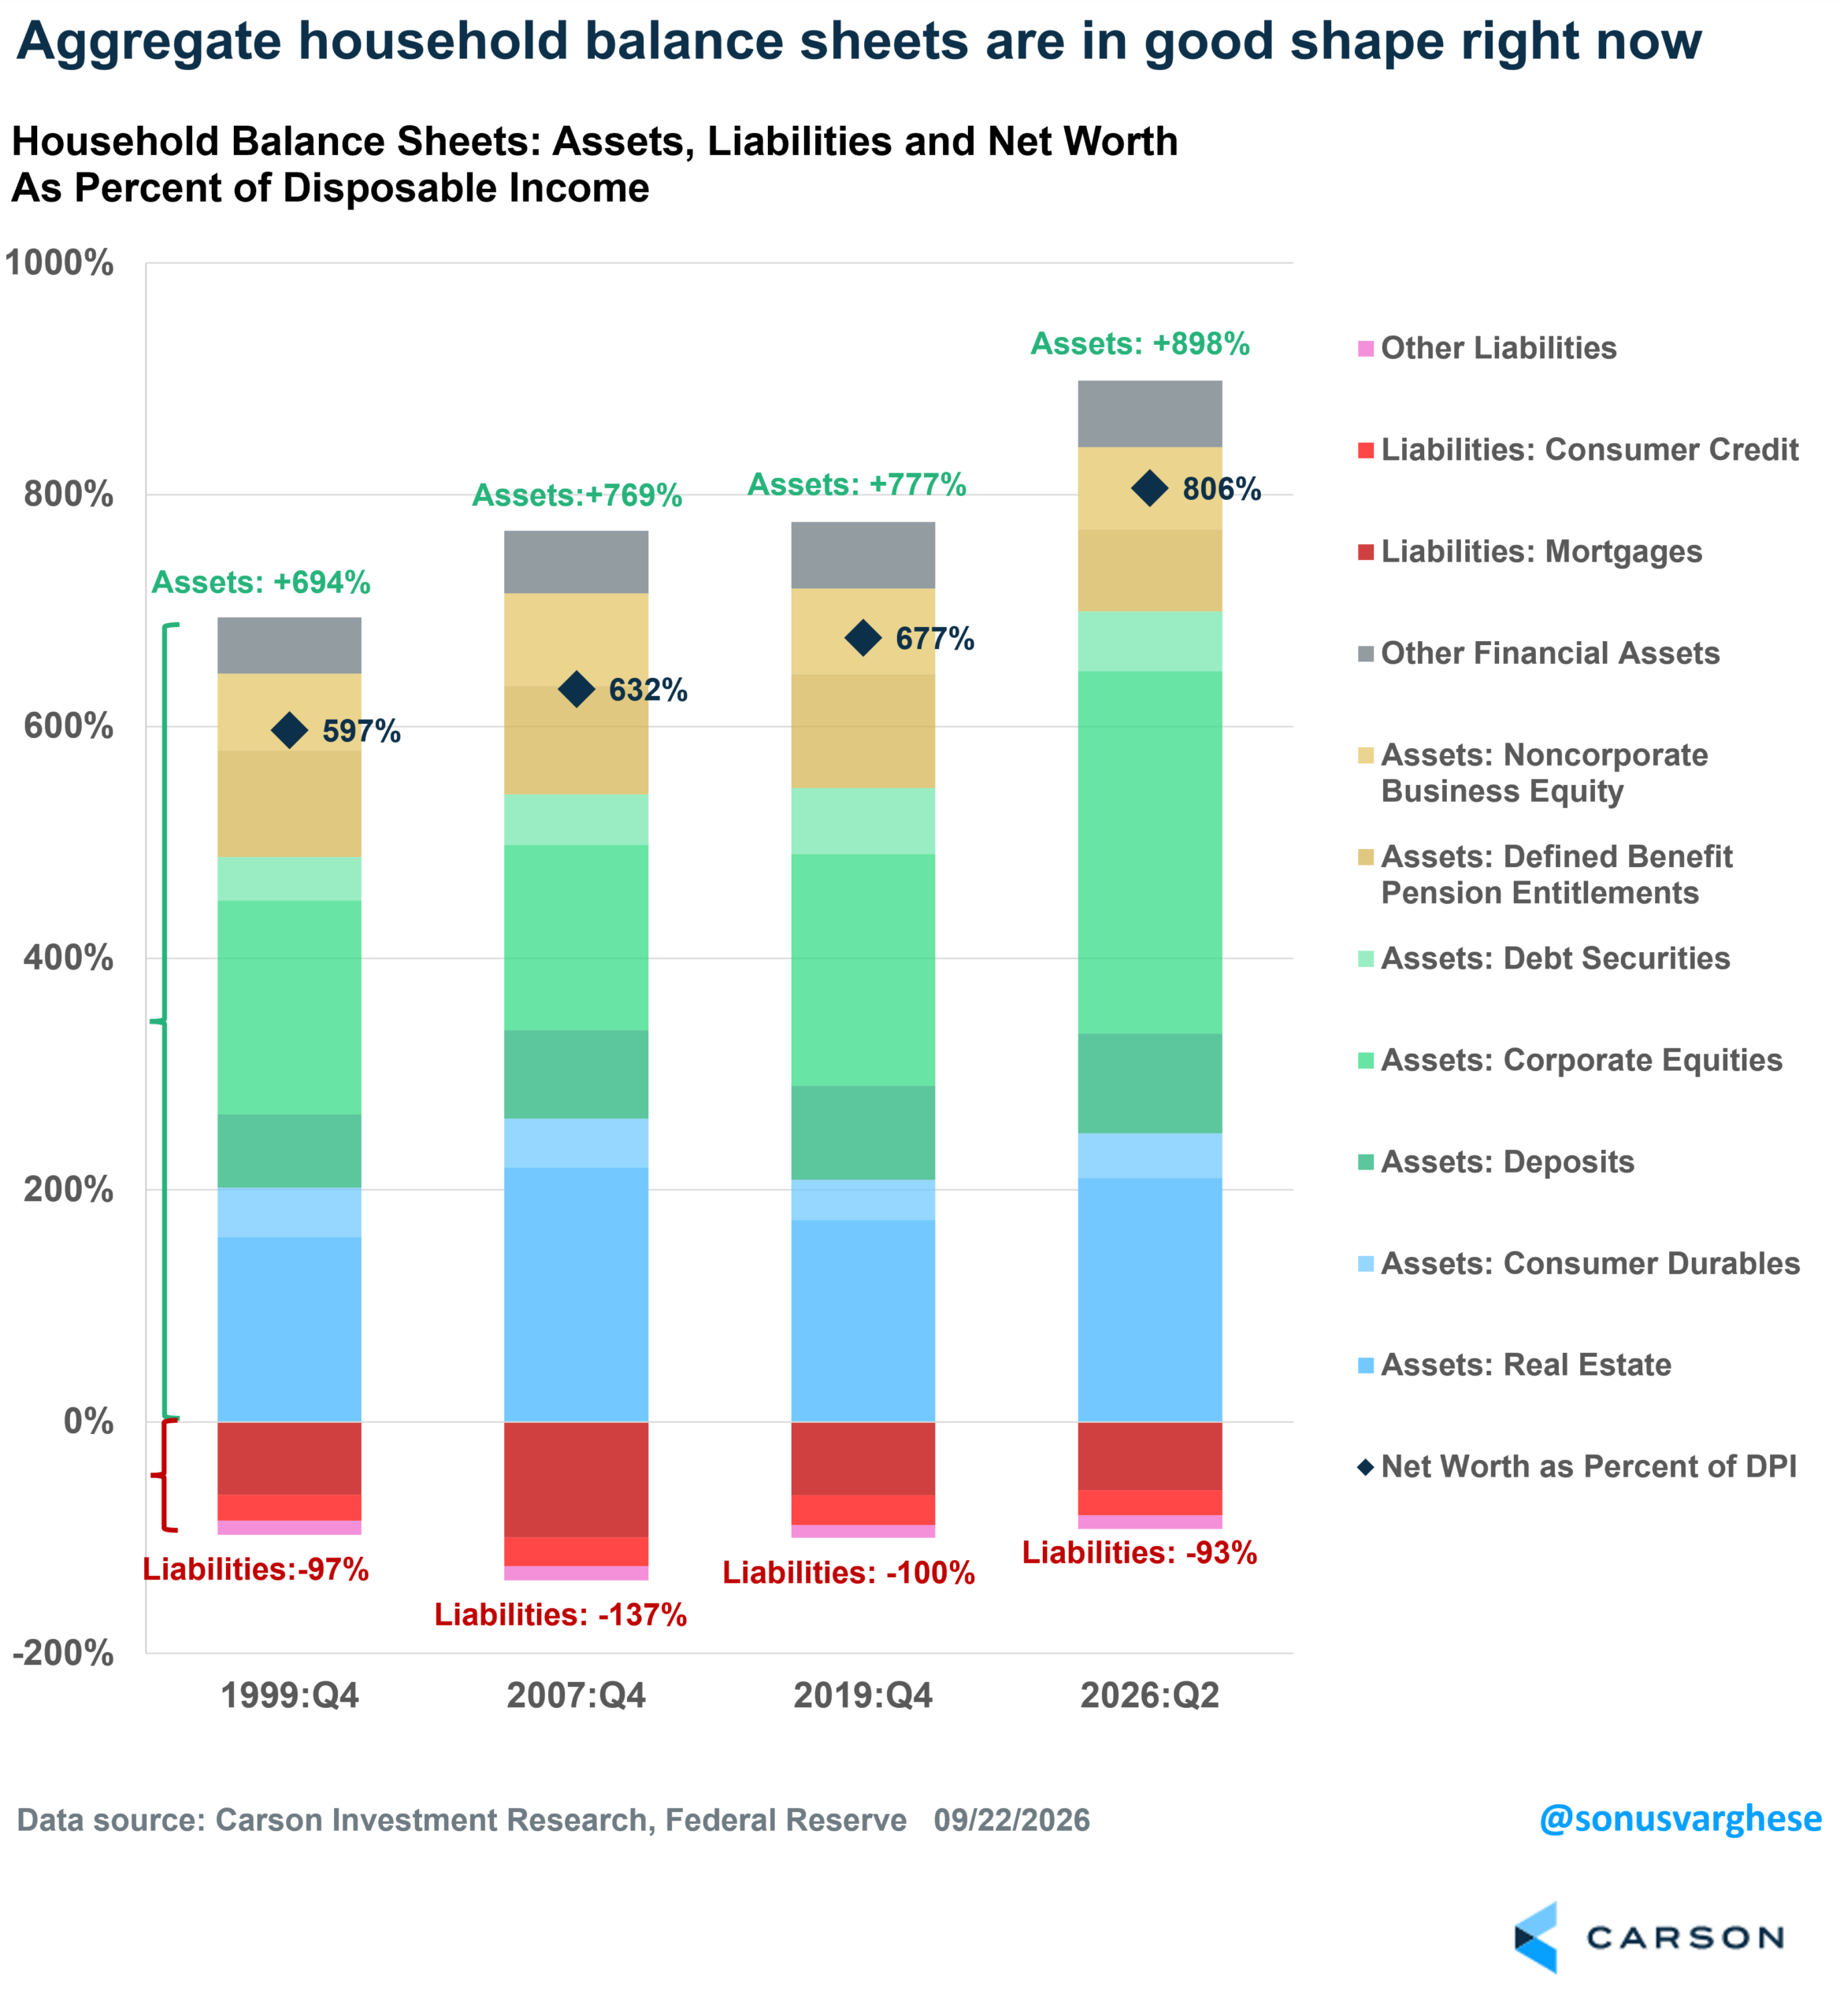
Here’s a chart I’ve been sharing for a few years, showing consumer balance sheets in really good shape (in aggregate). As of 2026 Q2, net worth was 806% of disposable income, up from 759% in Q1 and well above prior expansion peaks:
- 677% in 2019
- 632% in 2007
- 597% in 1999
The improvement over the last six and a half years is due to three factors:
First, liabilities are 93% of disposable income, versus 100% at the end of 2019 and 137% just before the financial crisis. Households were far more levered in 2007, making rising unemployment and falling home prices much more damaging. That’s not the case today. Liabilities relative to income show debt-service capacity; relative to assets, they show shock absorption. On that basis, household leverage fell to 10.3% in Q2 from 10.8% in Q1.
For perspective:
- Q4 2019: 12.9%
- Q4 2007: 17.8%
- Q4 1999: 14.0%
The peak was 20.2% in 2009 Q1. The last lower reading was in 1962 Q1. Households have essentially unwound the leveraging cycle that ran from the mid-1960s through the financial crisis.
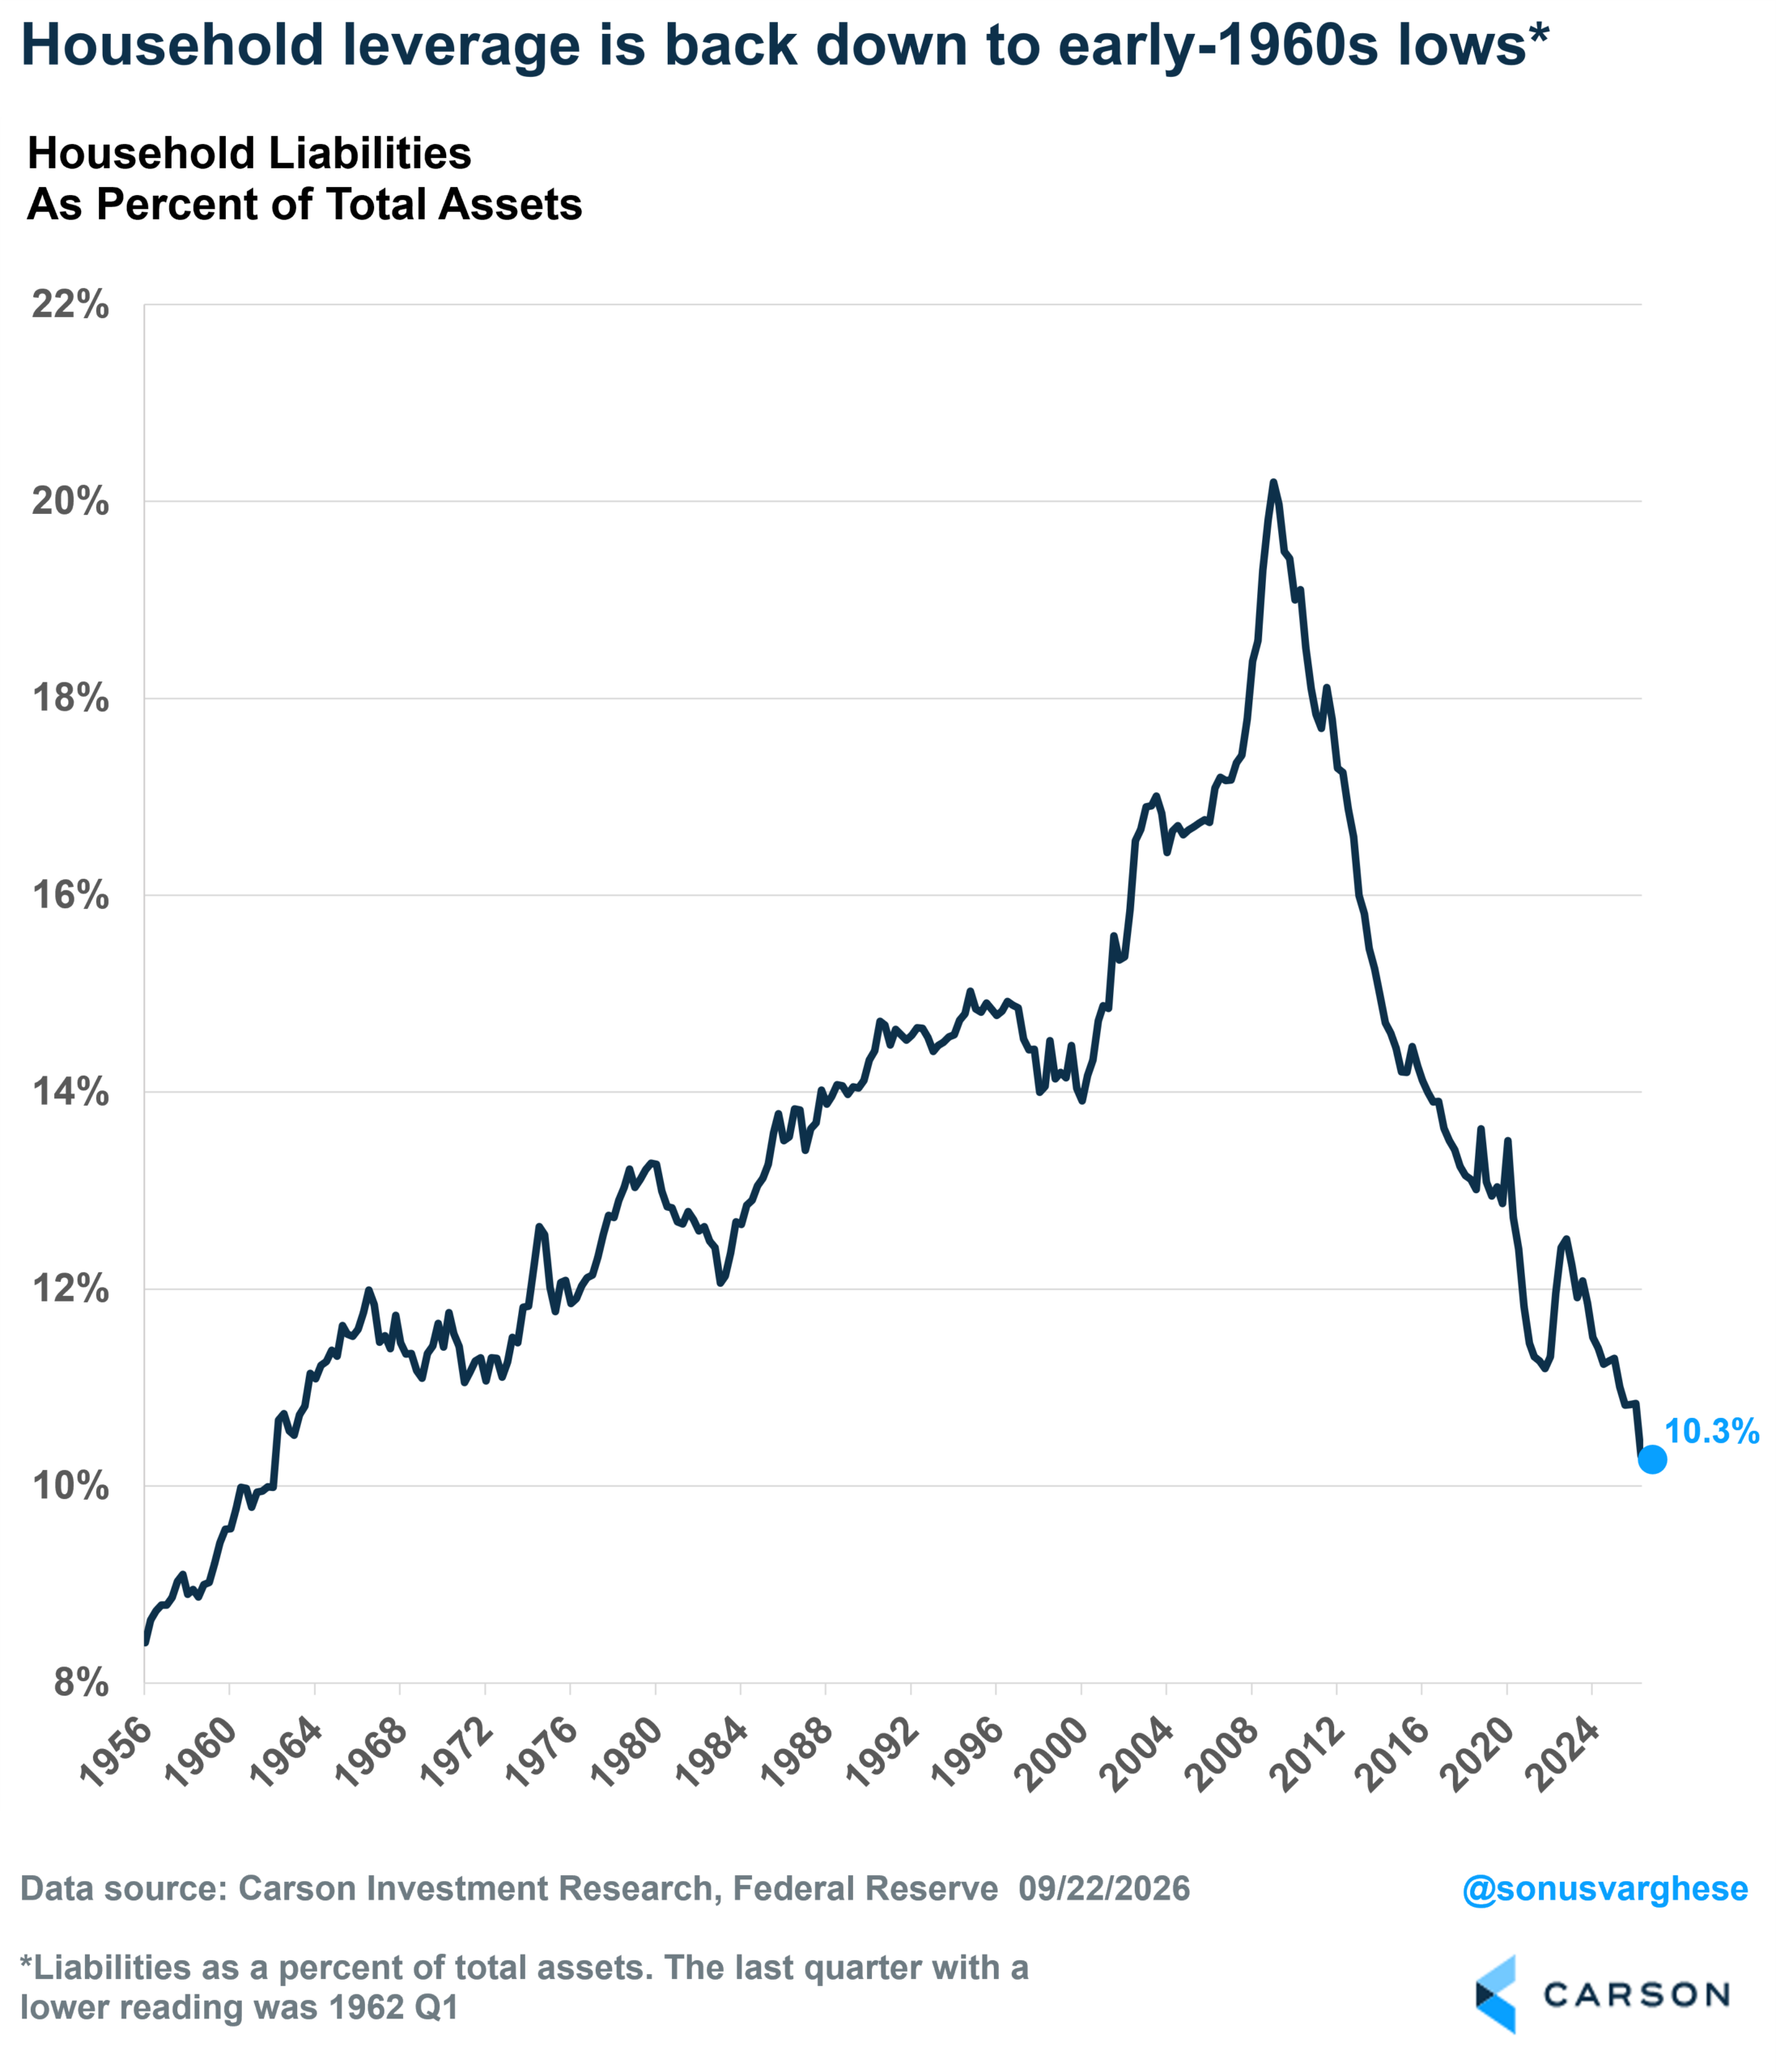
One caution: This ratio improves when asset prices rise, not just when debt falls. A big enough drop in stocks or homes pushes it higher mechanically, without any new debt. That gets to the other two reasons balance sheets improved.
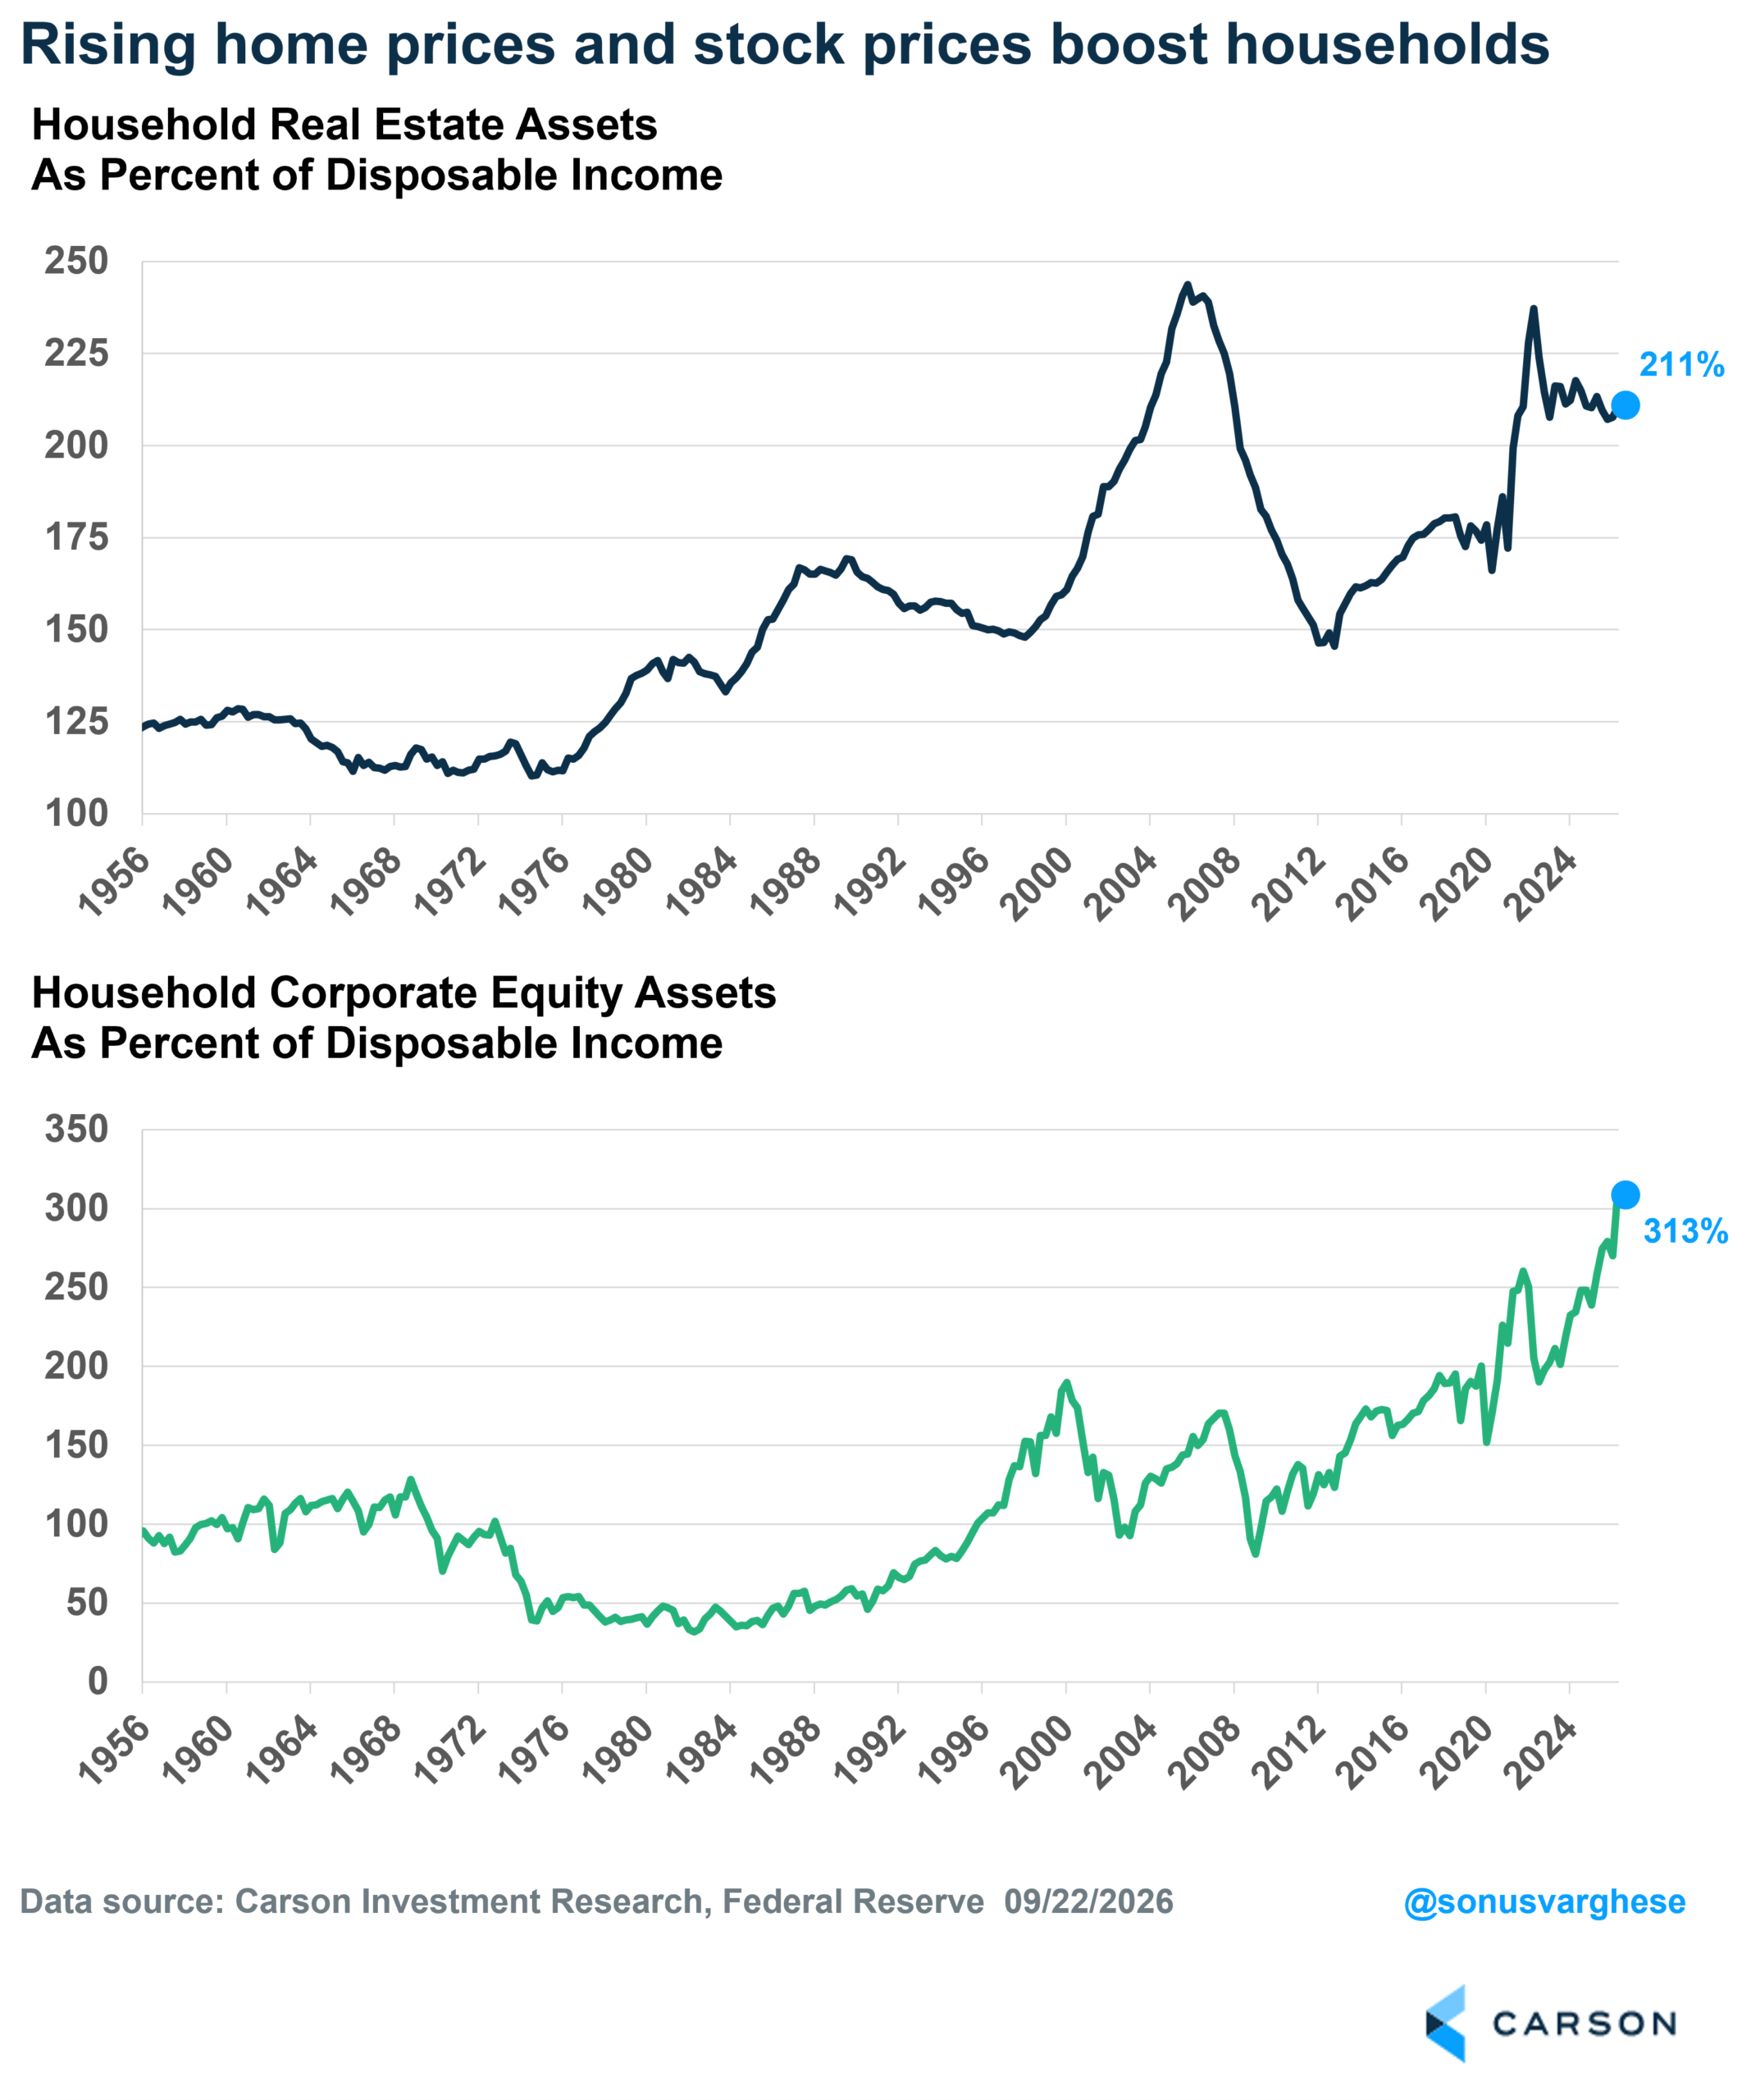
Second, real estate assets are 211% of disposable income, up from 174% at the end of 2019 and near 219% in 2007. Real estate peaked at 244% in 2005 Q4 and hit 237% again in 2022 Q2. It has drifted lower since as incomes rose while home prices flatlined.
Third, equity holdings are 313% of disposable income, up from 200% at the end of 2019 and 160% in 2007. Even at the dot-com peak, they were just 190% (2000 Q1).
What Could Upset the Apple Cart? A Bear Market
A sustained bear market would be extremely detrimental to household balance sheets. Rising stock prices have been the biggest driver of net worth over the last five years.
- Equities are now 38.9% of net worth, a record going back to the start of the data in 1952.
- It was 29.6% at the end of 2019.
- It was 25.2% at the end of 2007.
- It was 30.9% at the end of 1999.
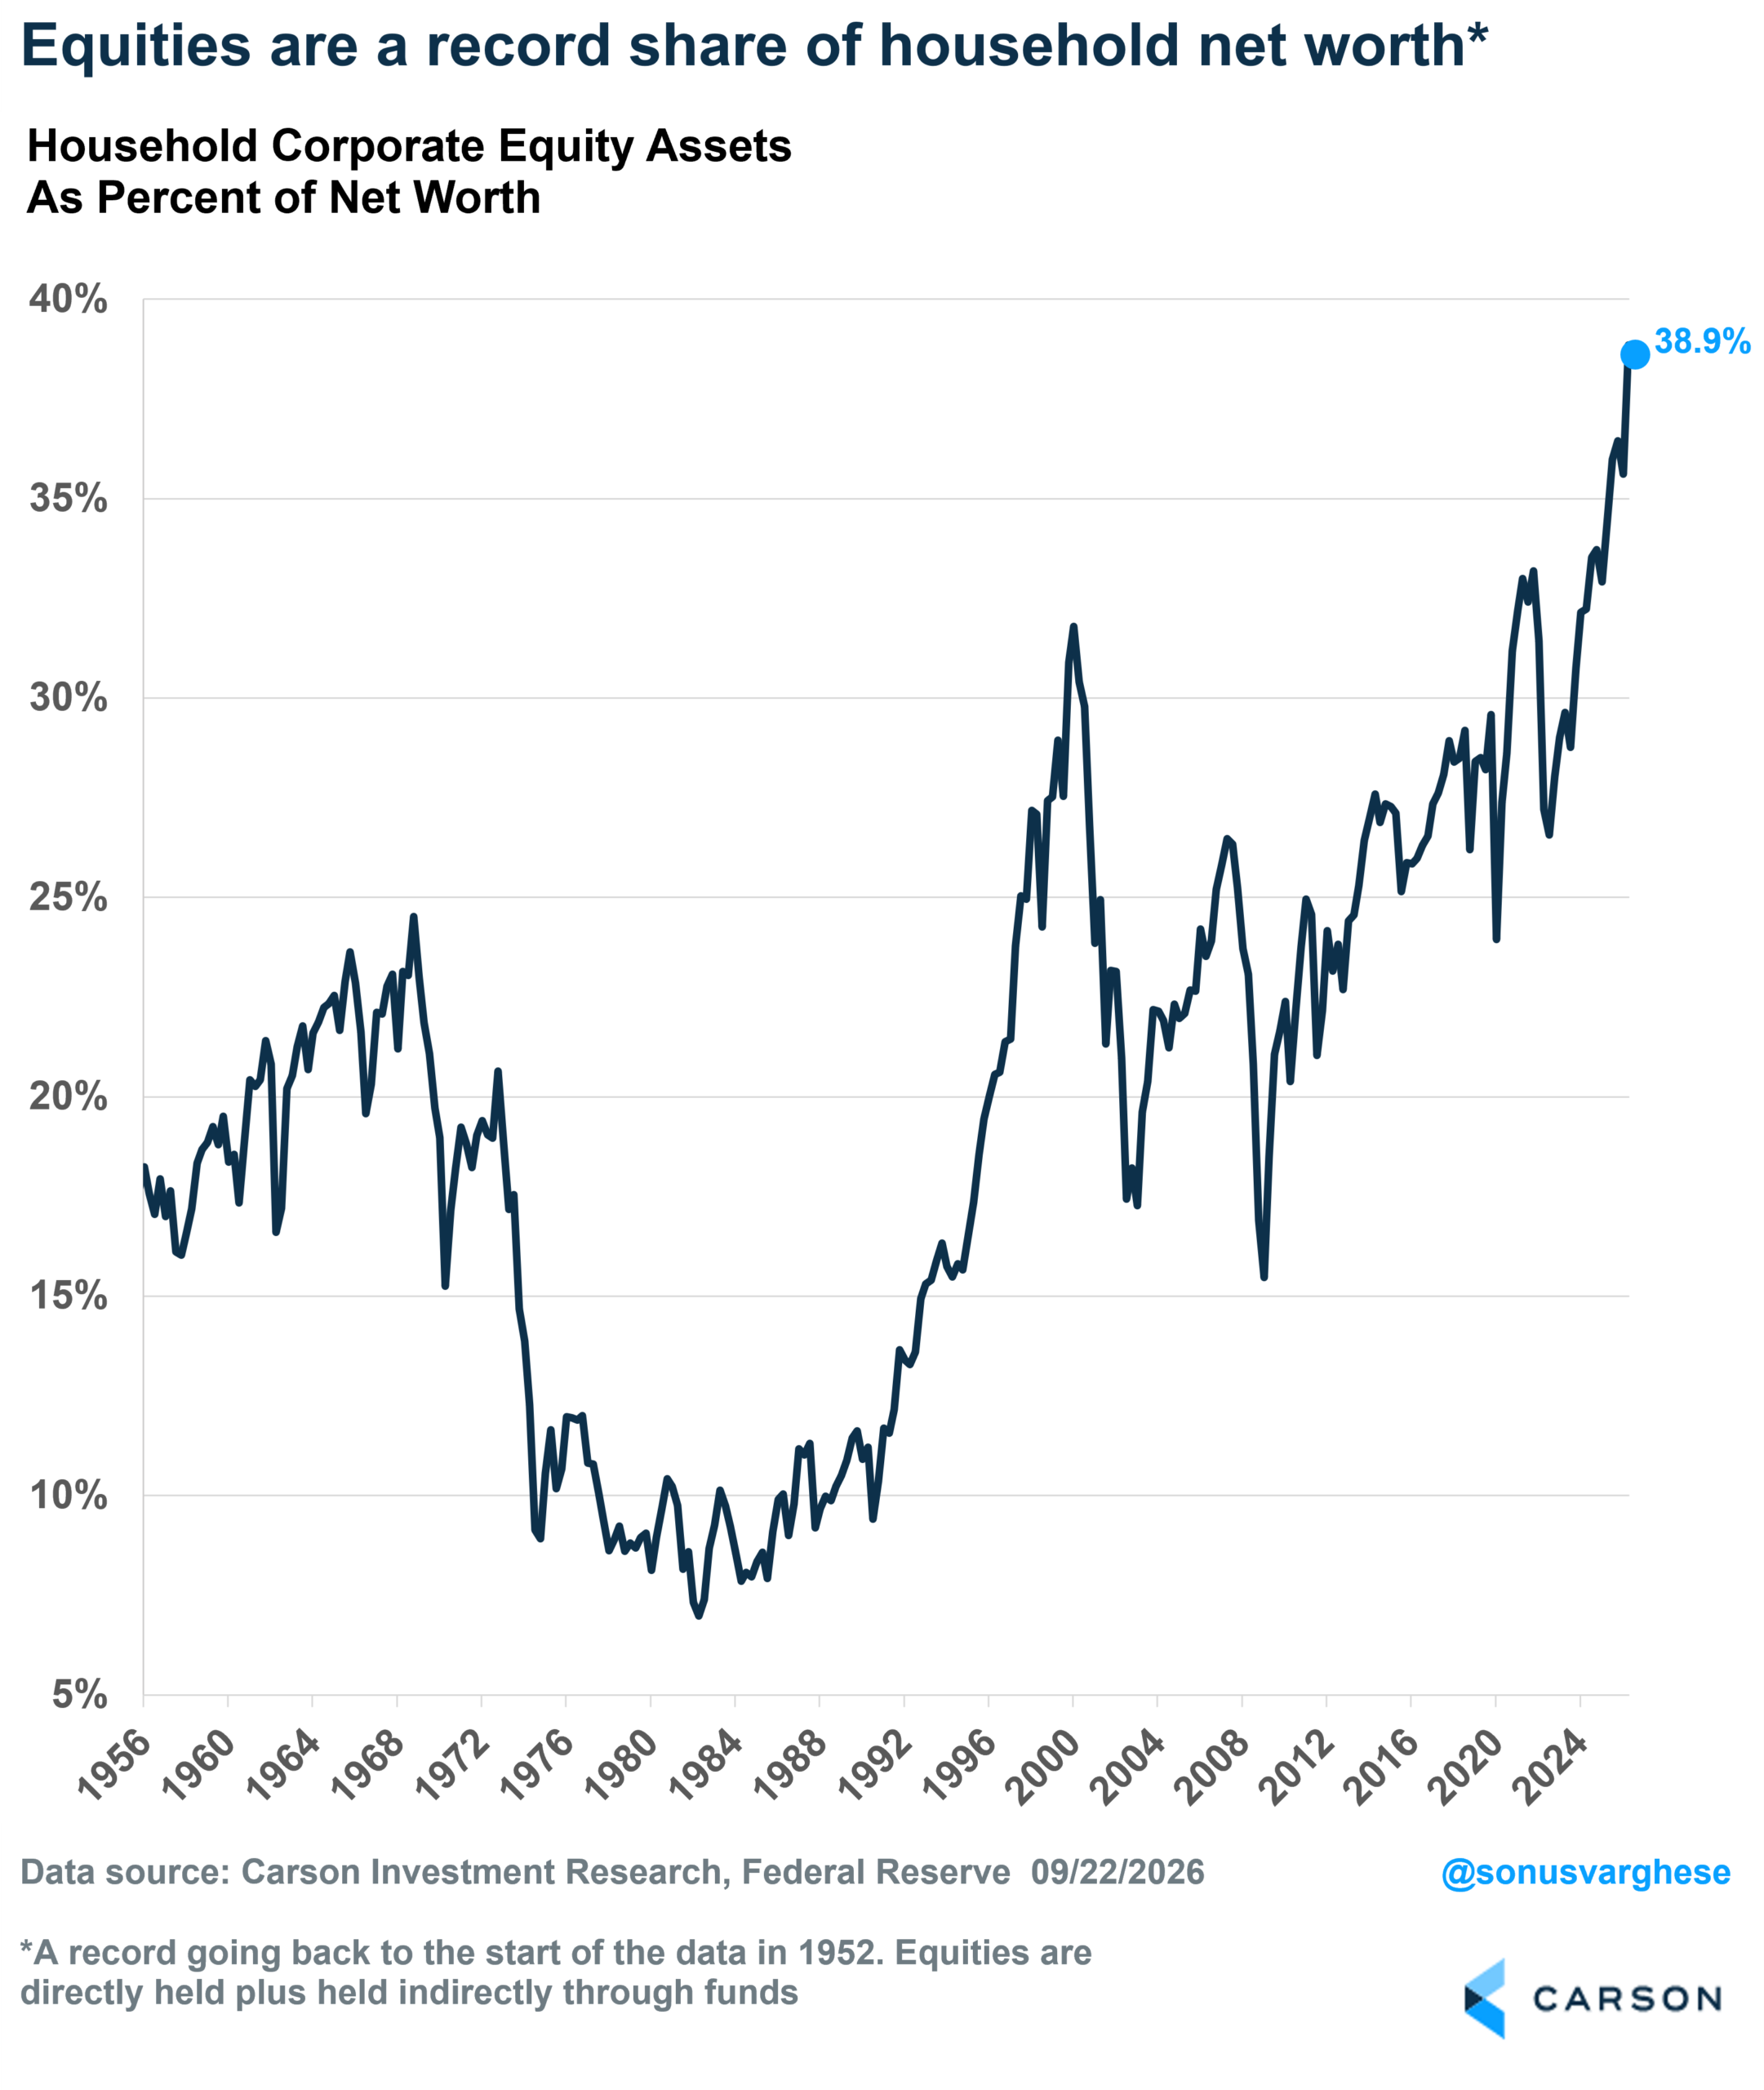
That leaves household balance sheets unusually exposed to a volatile asset. We got a demonstration two quarters ago: stocks pulled back in Q1 and net worth fell about 8 percentage points of disposable income, even without added leverage. Q2 ran the mechanism in reverse, with net worth gaining 47 points as stocks hit new highs.
Obviously, this feeds on itself, and a sustained decline could put us in a vicious cycle of:
- Bear market ->
- Weaker household balance sheets (including from falling home prices) ->
- Lower spending ->
- Lower revenues and hiring ->
- Rising unemployment ->
- Falling aggregate income ->
- Lower spending ->
- Lower profit growth, if not an outright decline ->
- Back to top
Once the process starts, it can feed on itself, so an external catalyst is needed to put sand into this negative feedback loop. That’s not our base case. We can still get volatility, but for stocks to materially damage household balance sheets, we likely need a sustained bear market lasting much longer than recent ones.
Big picture: Leverage is the best it’s been in sixty years. Net worth is setting records again, driven entirely by the asset side. Households are being marked to market rather than borrowing their way into trouble. That means the thing to watch from here is the S&P 500, rather than household debt. The economy may be more tied to the stock market (and vice versa) than ever.
For more content by Sonu Varghese, Chief Macro Strategist, click here.
9142185.1. – 23SEPT26A