With Thanksgiving next week, we decided to do something a little different. Each of us picked the 2026 chart we’re most grateful for and explained why, much like our favorite charts from the first half. It’s a good year to do it. AI stocks have been hit hard since October 6, the Fed is raising rates again, and a lot of investors feel nervous even though S&P 500 earnings are on track for one of their best years in a long time. A few good things are easy to miss when the headlines look like that, so we wanted to point some out and show our gratitude.
There’s a Whole Market Outside the AI Trade
Sonu Varghese, Chief Macro Strategist, kicked things off by reminding everyone that the S&P 500 and “the market” aren’t the same thing anymore.
“When we talk about the ‘stock market,’ we’re usually referring to the S&P 500. Historically, that made sense because it was broadly diversified. Today, more than half the index is in technology and tech- or AI-adjacent stocks, so when those stocks stumble, the index feels it. You don’t have to invest in the stock market the way the S&P 500 is built. You can diversify beyond the index.
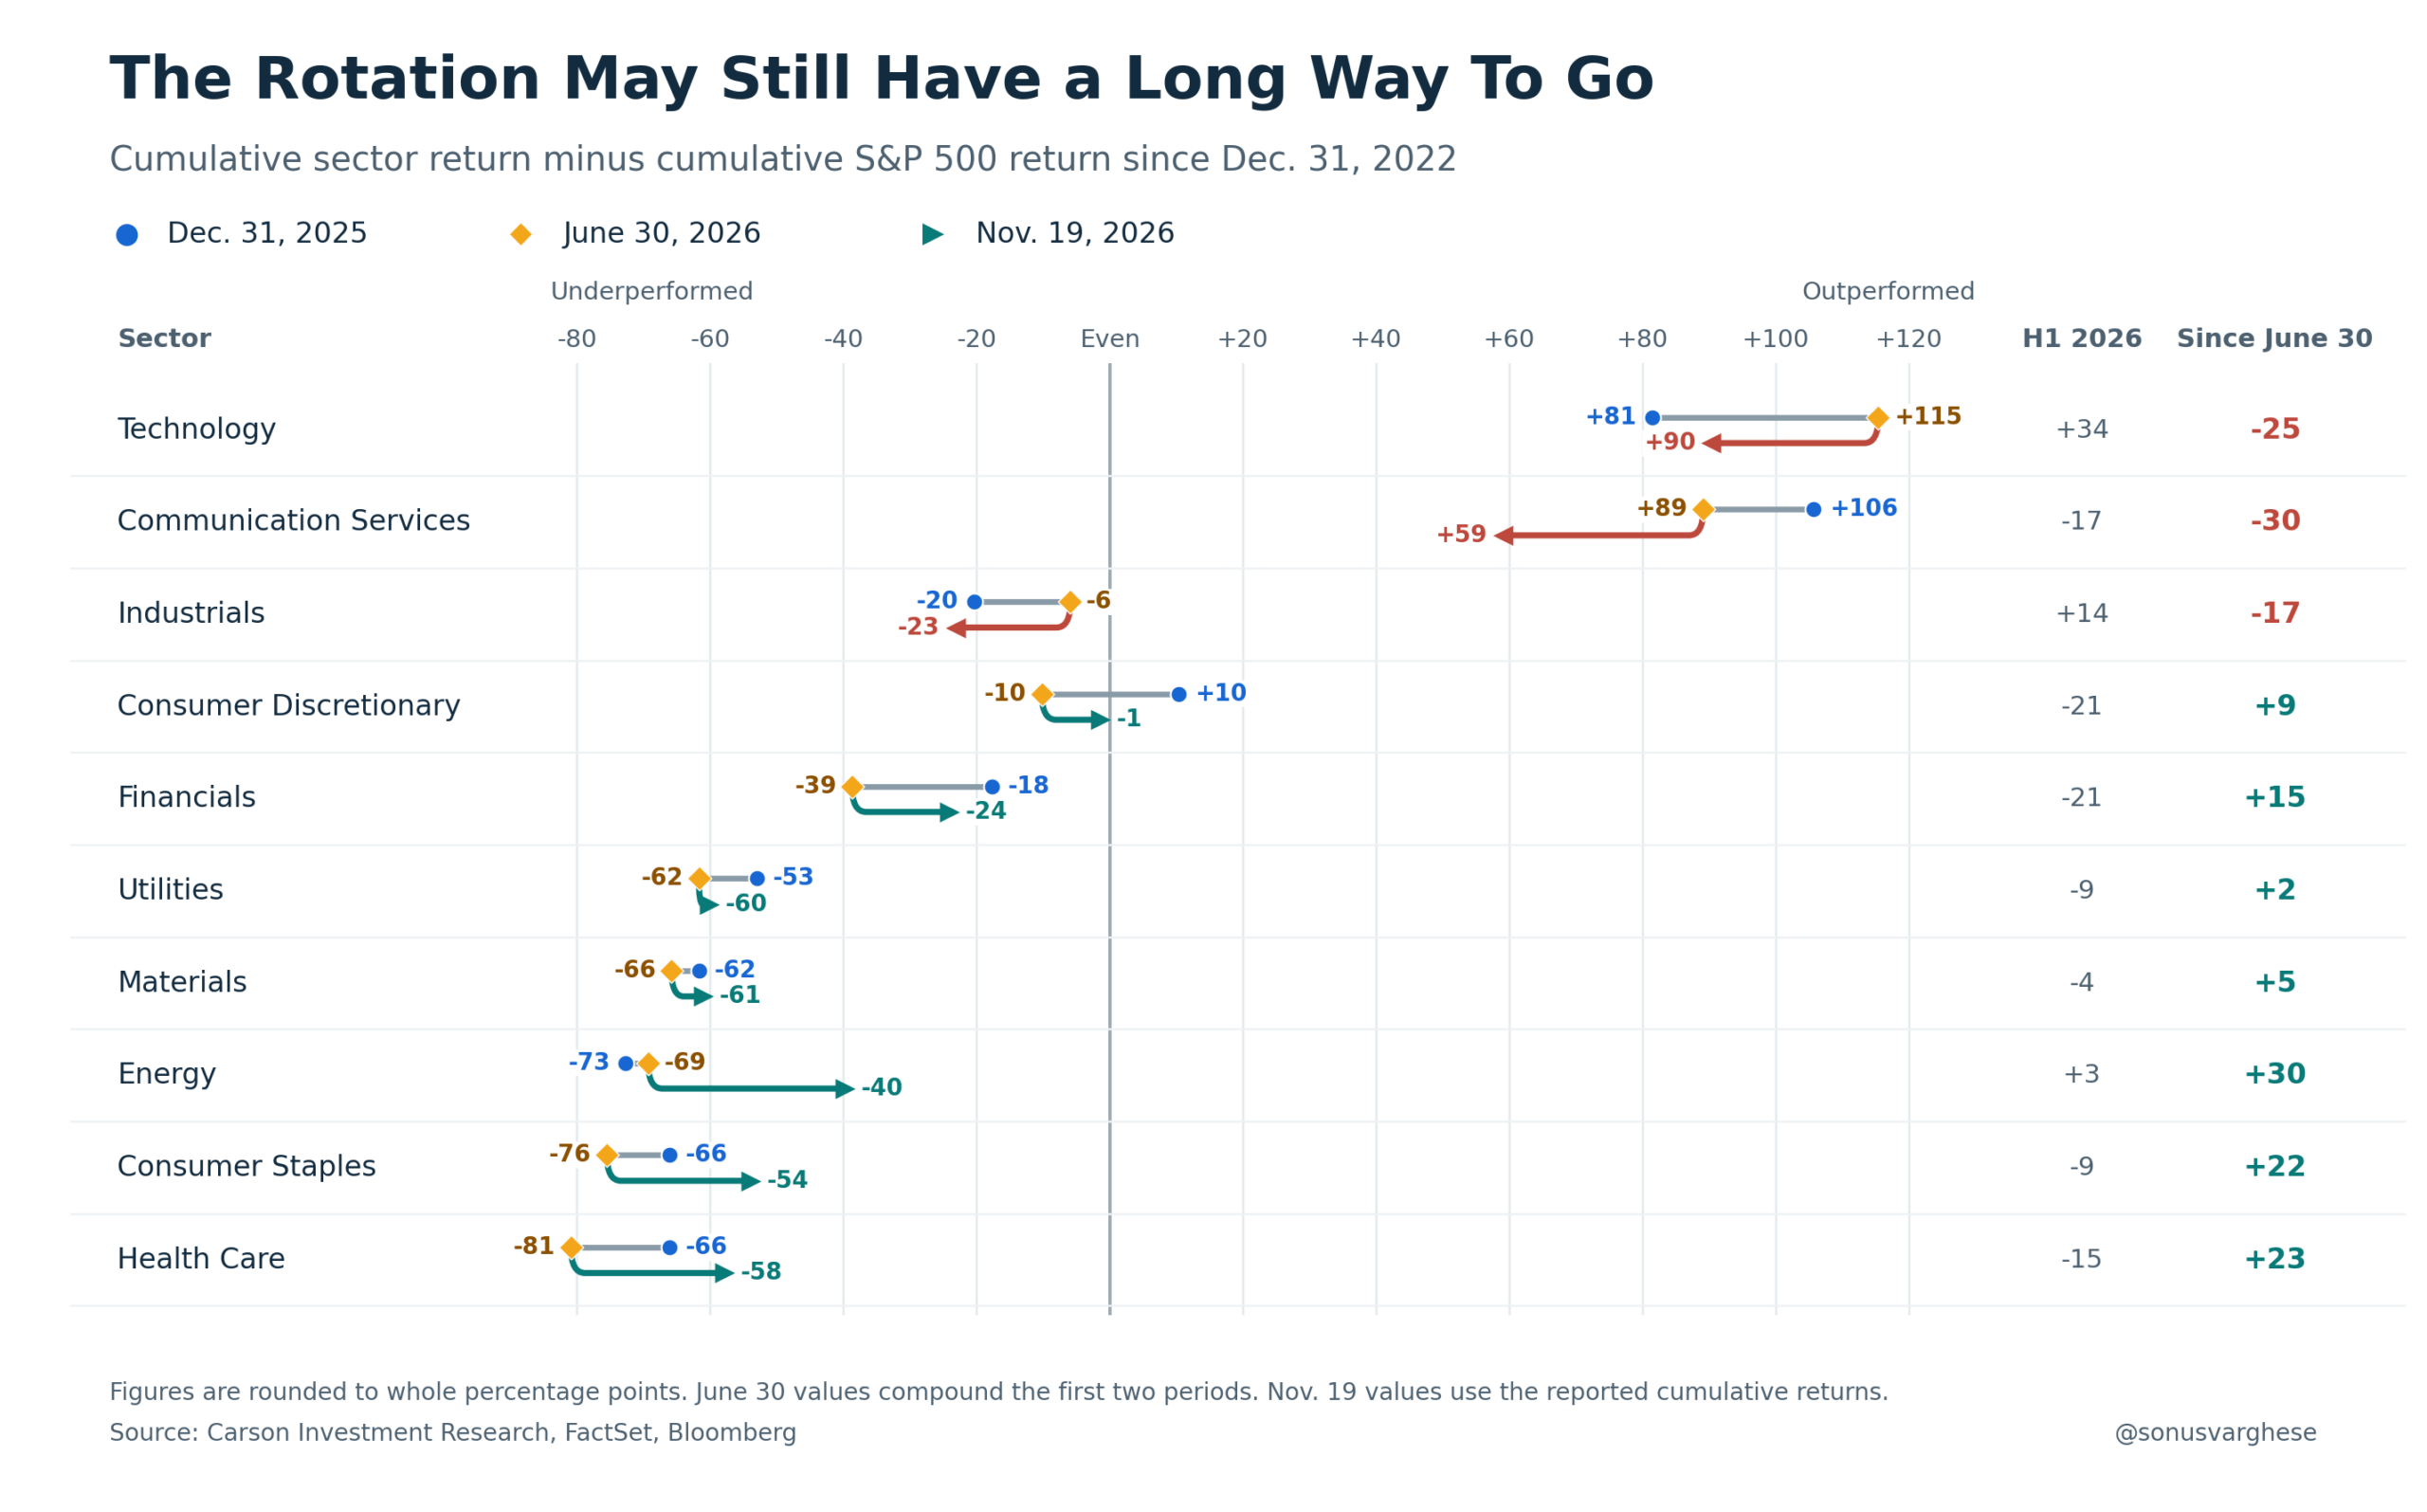
The good news is that the tech and AI selloff since October 6 hasn’t hit sectors less tied to AI as hard. Think health care, financials, energy, and consumer staples. In fact, we’ve seen a rotation since the end of June, but it may still have a long way to go. Tech (and communication services) built up a massive performance lead in the three and a half years from the end of 2022 to June 2026, and these other sectors have made up only some of that ground.
I have no idea if we’re in a bubble (it feels like one), let alone how far along we are or when it might pop. If you plan to time the top and get out before everyone else… we wish you good luck. We’re increasingly comfortable diversifying judiciously beyond AI, even if it means missing some upside. We think diversification is more important than ever, especially within equities. There’s a whole market of stocks outside the AI trade, and plenty of them are doing just fine.”
Scientific Breakthroughs Power Returns
Blake Anderson, Director, Portfolio Management, took Sonu’s point about health care and found one of its best-performing corners.
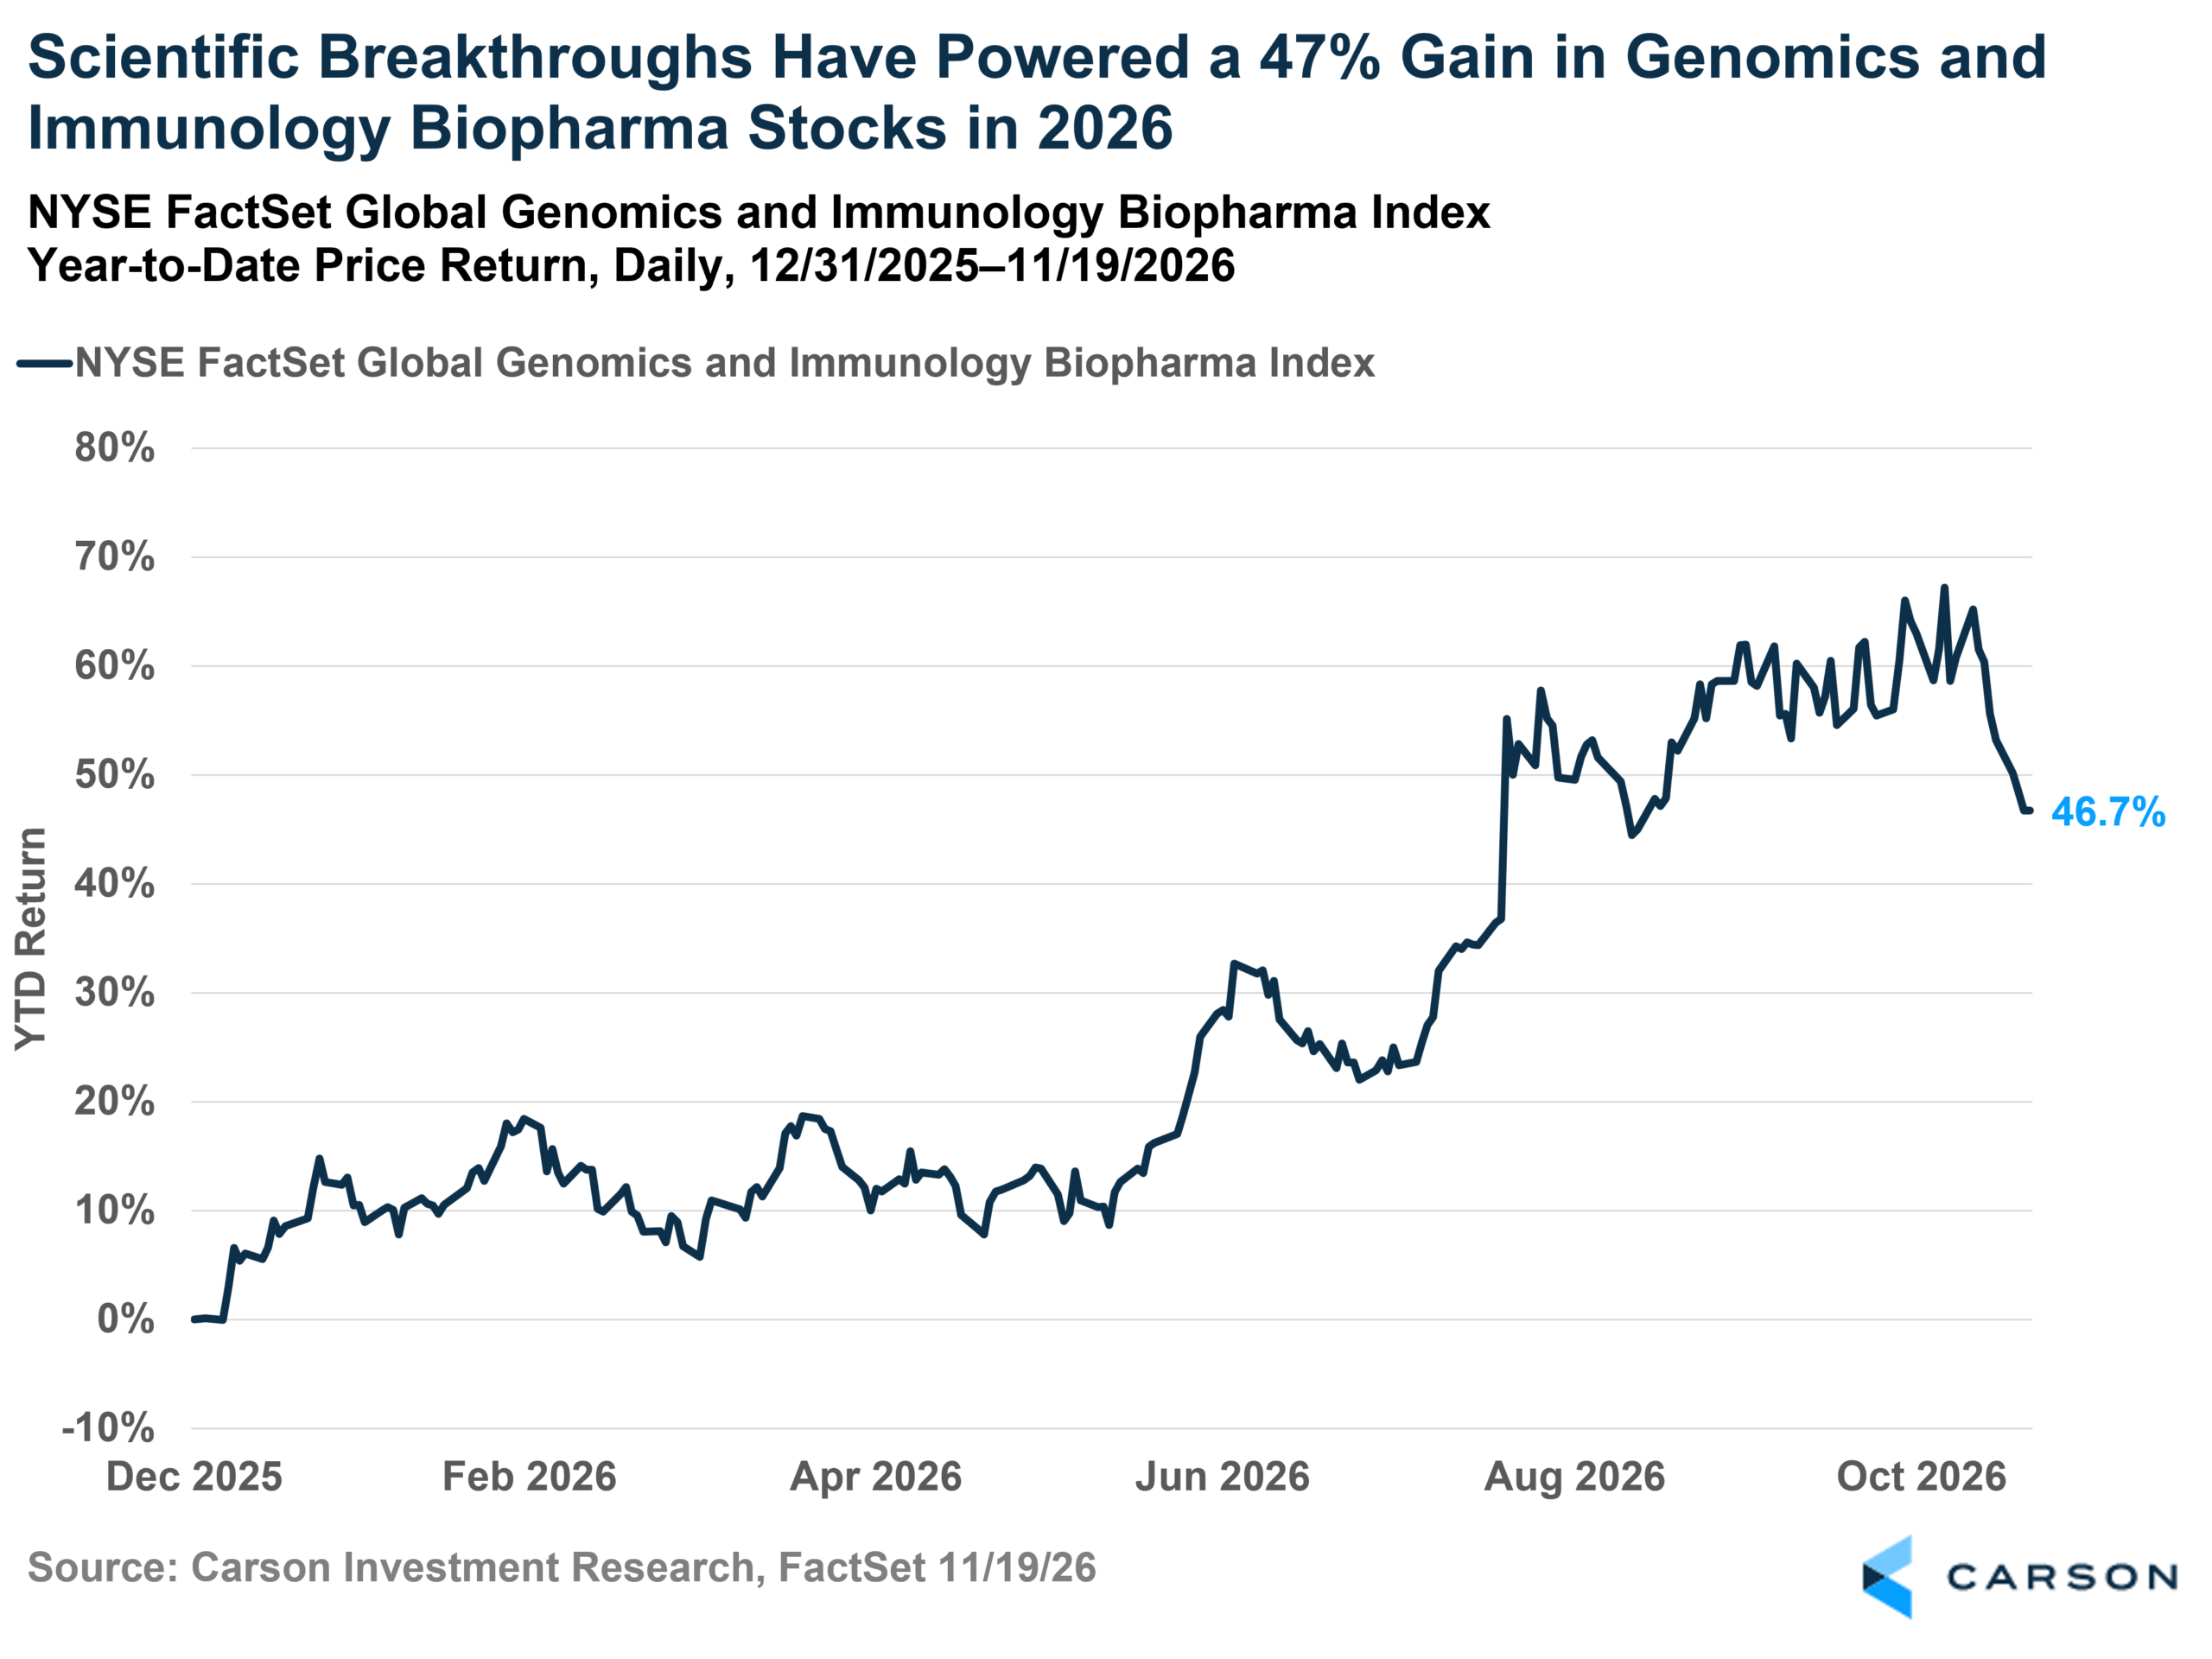
“As Sonu mentioned, healthcare has been one of the standout sectors this year. One corner of the market that I’m thankful for is an industry within health care, the Genomics and Immunology Biopharma industry. As shown below, an index that tracks this industry has seen healthy gains so far in 2026.”
“This corner of the health care market is typically pursuing research in the fields of mRNA, siRNA, and NGS treatments, among other promising technologies.
Scientific breakthroughs this year have helped power some of the robust returns investors have seen in this industry. Notably, personalized mRNA oncology treatments progressed through key clinical trial endpoints and showed improvements relative to current standards of care.
I’m thankful that companies are pursuing research in such potentially groundbreaking treatments to give us all a chance at healthier lives.”
Value Stocks Have Had a Big Year
Grant Engelbart, VP, Investment Strategy & Research, zoomed out to growth versus value, where the gap this year has been enormous.
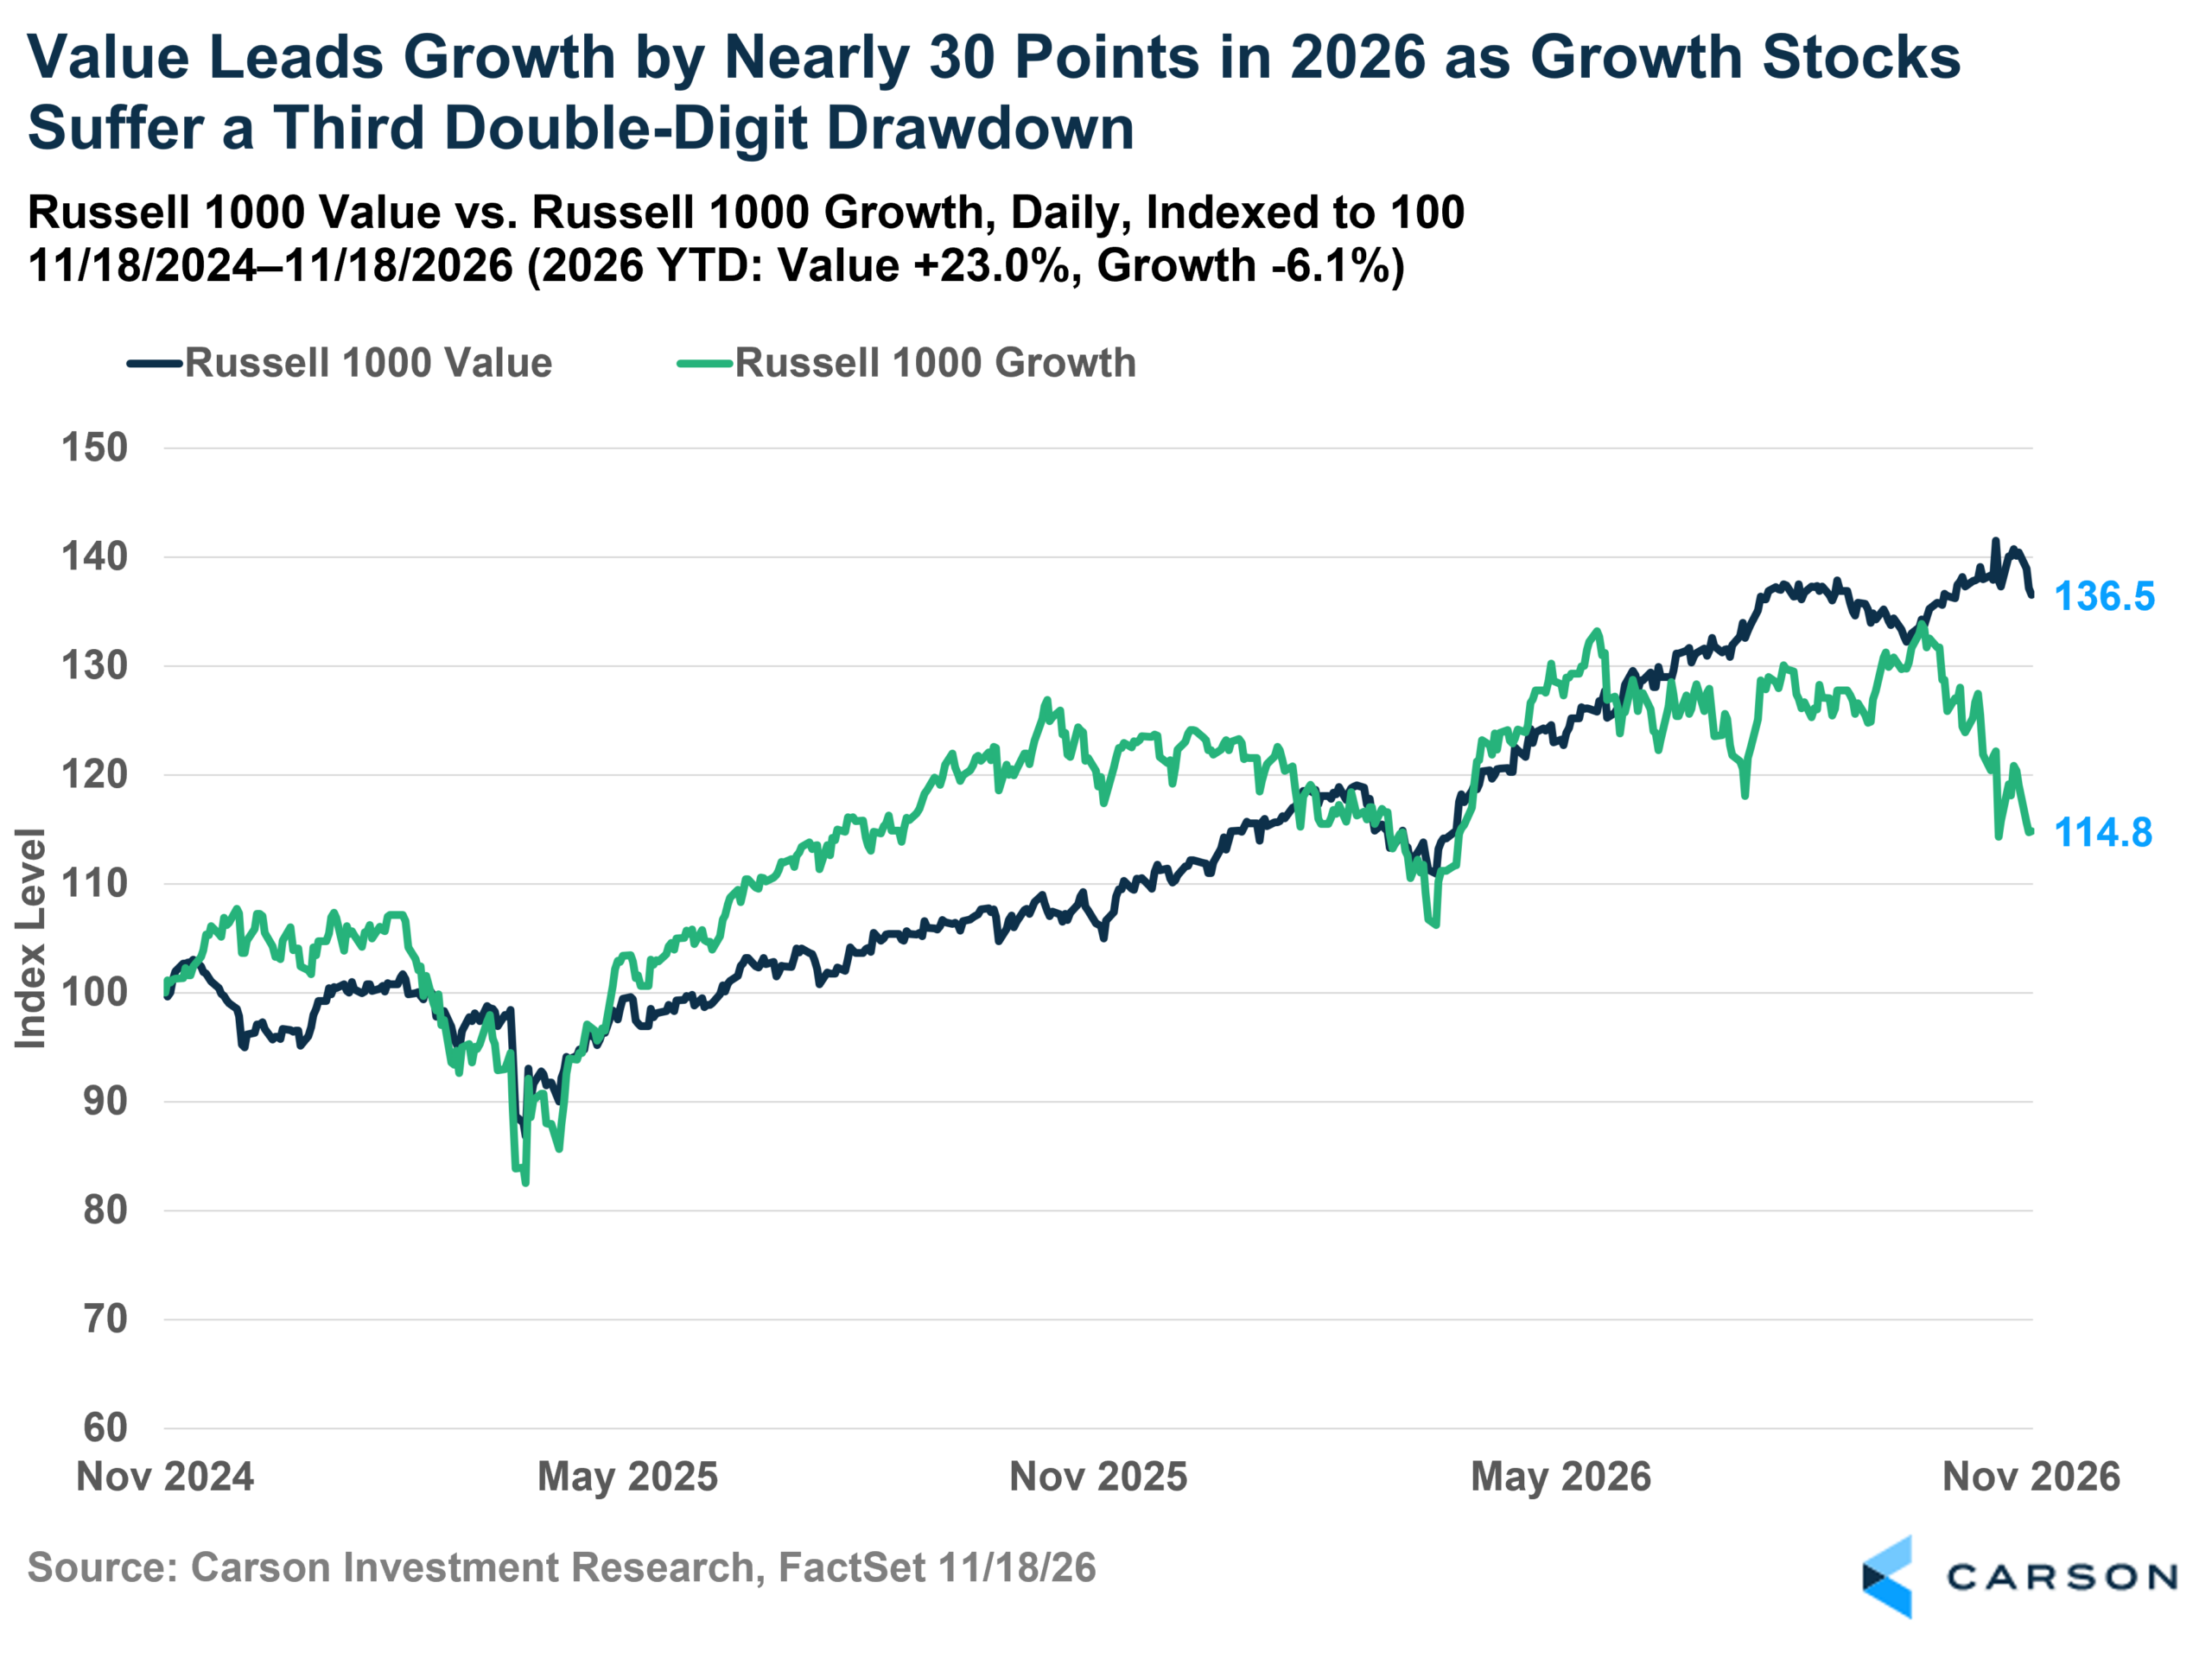
“Since rebounding from the lows of 2022, growth stocks have been the darling of the global stock market, bolstered by rising concentration in artificial intelligence names. Increasing valuations, concerns about future spending, and uncertain growth prospects have led to increased volatility in growth stocks. Growth stocks are now in their third double-digit drawdown in 2026 alone, and a second pullback deeper than 15%. Parts of the value universe are increasingly becoming tied to the AI wave. Still, inflation and growth-sensitive areas within value have led to value outperforming growth by nearly 30 percentage points year-to-date.”
Earnings Growth Is Spreading Beyond the Mag 7
I’ve spent much of this year writing our weekly Earnings Check-In, so my pick had to be an earnings chart… it just feels right. The one I’m most thankful for compares the Magnificent 7 with the other 493 companies in the S&P 500.
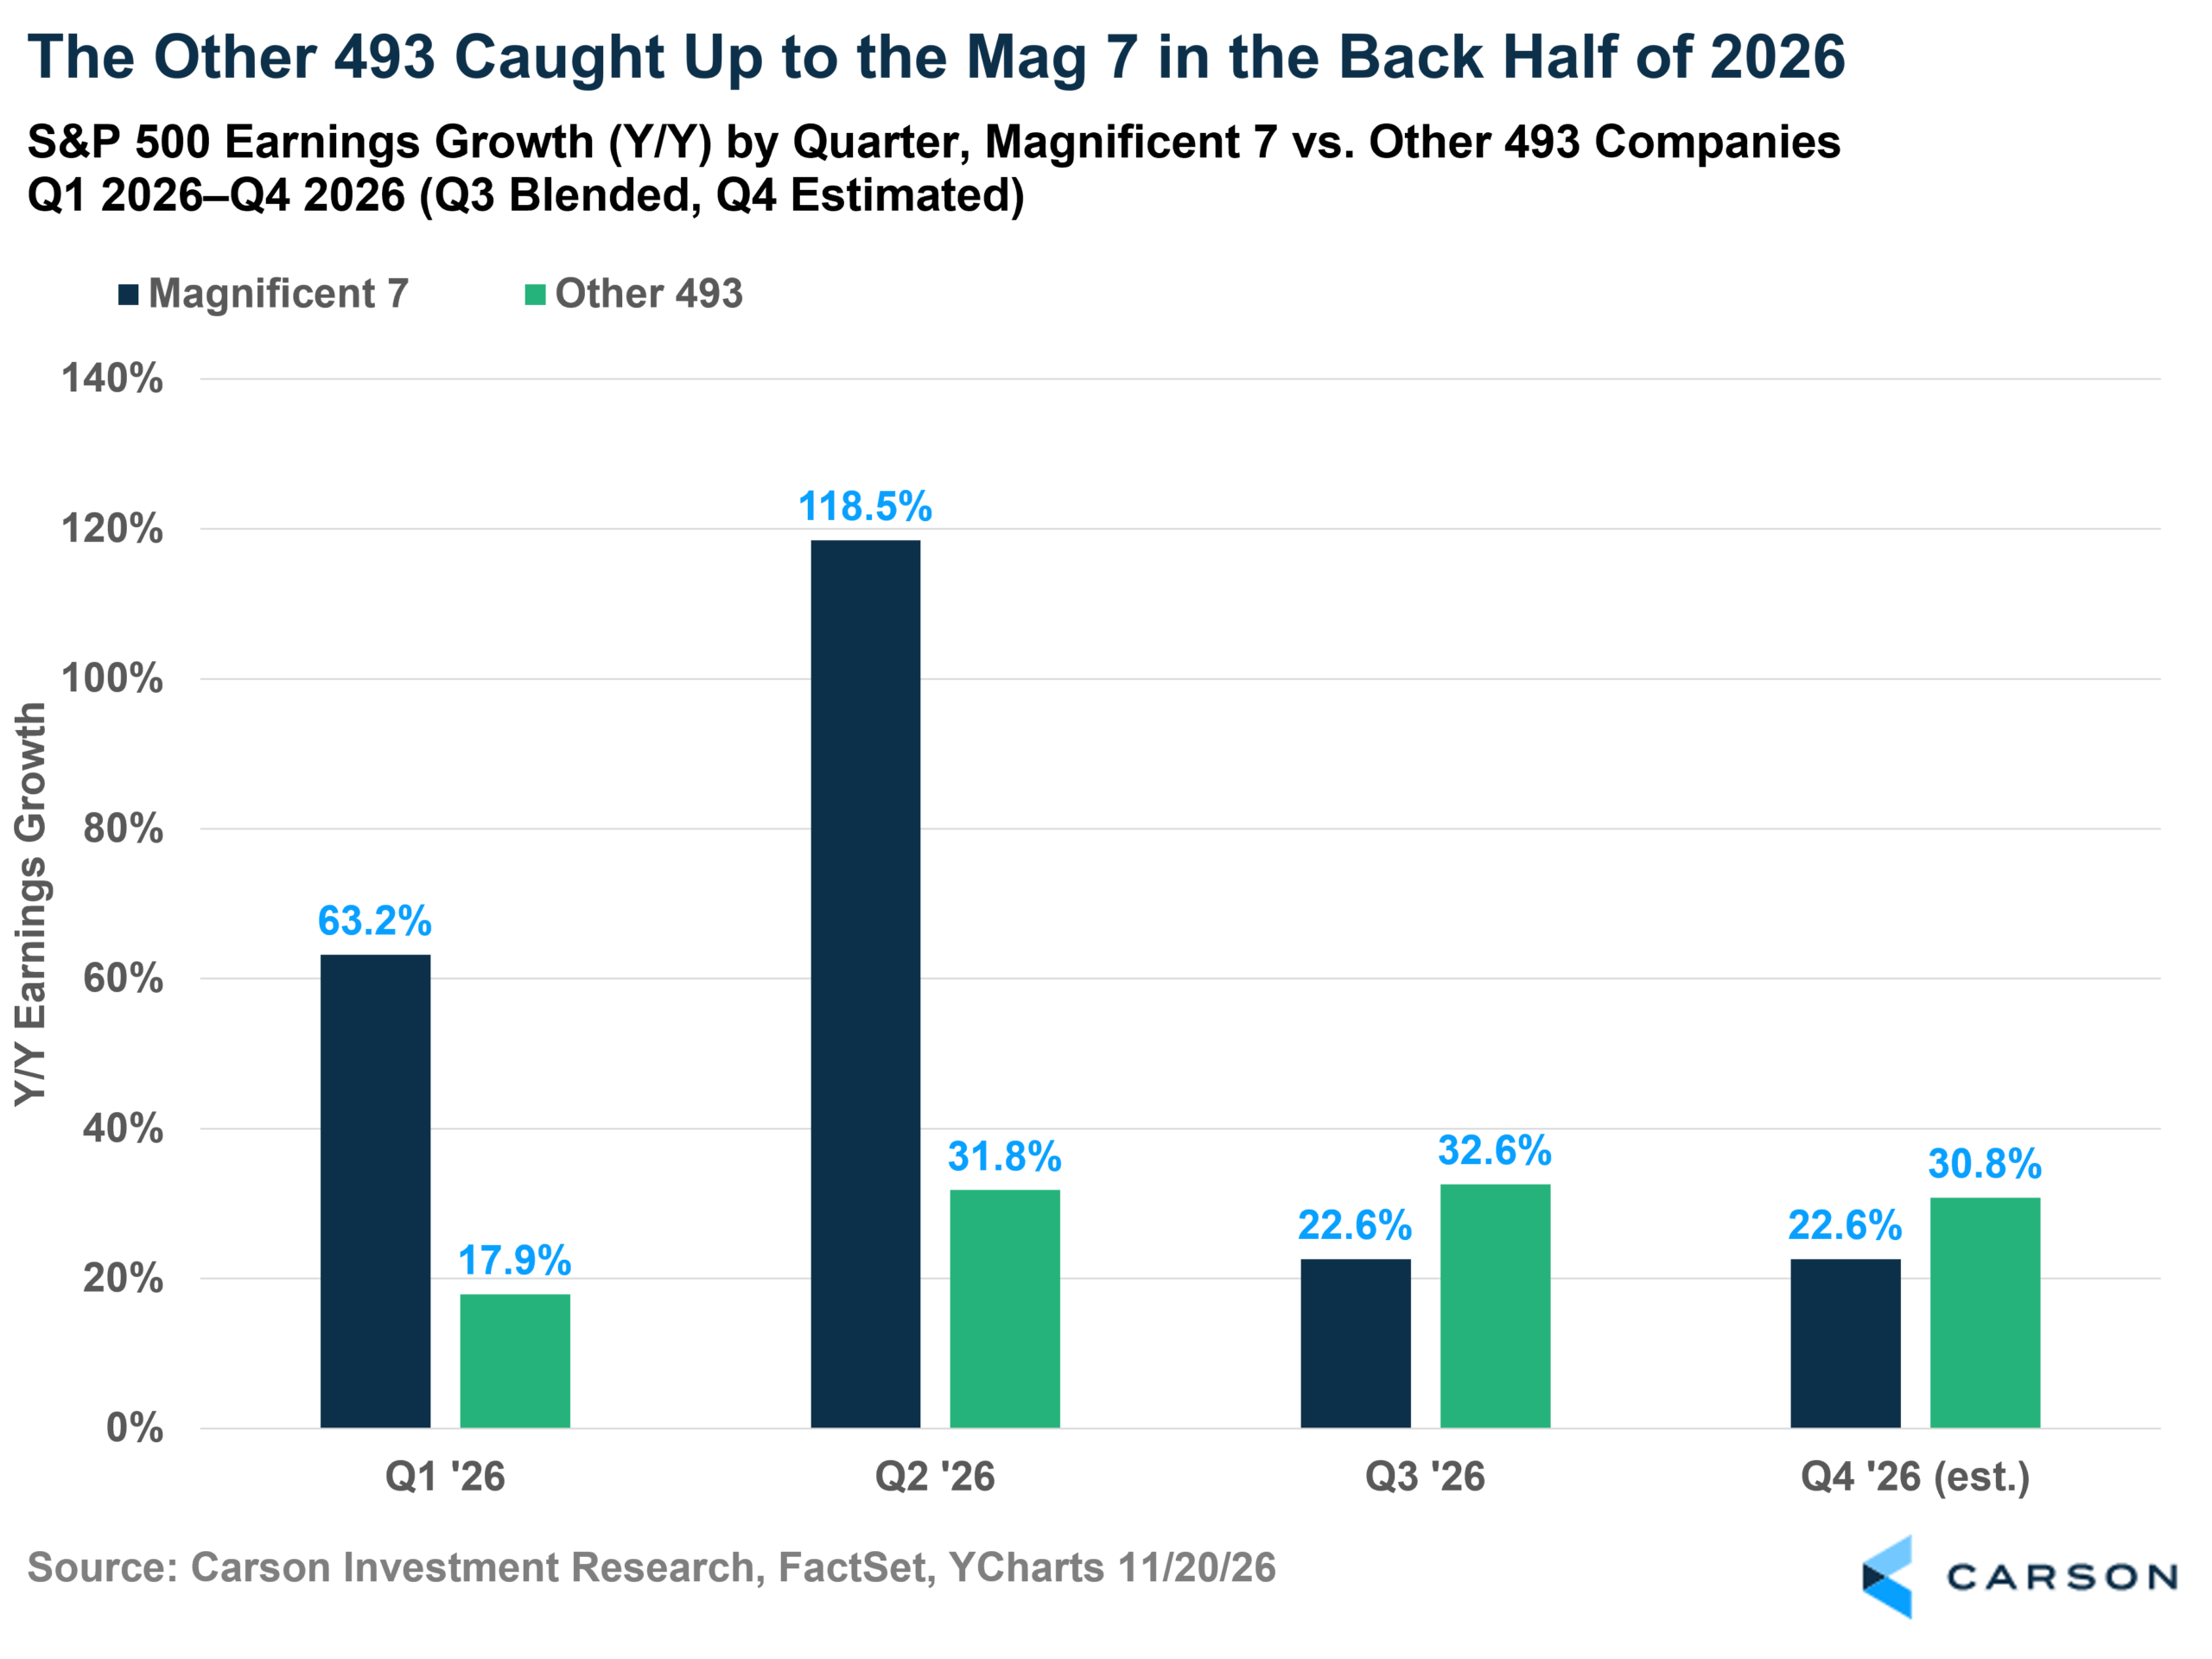
For the first half of the year, the Mag 7 did most of the heavy lifting. Their earnings grew 63.2% year over year in the first quarter and 118.5% in the second. Large investment gains at two of the seven inflated that second number, and without those two companies, the Mag 7 grew 43.2%.
Then the rest of the market caught up. The other 493 grew earnings 32.6% in the third quarter, compared with 22.6% for the Mag 7, according to FactSet. That’s the second straight quarter above 30% for the 493, and analysts expect them to outgrow the Mag 7 again in the fourth quarter. To me, this is what makes Sonu’s rotation easier to trust. Money moving into the rest of the market makes a lot more sense when the rest of the market is growing its profits this fast.
Stay on Top of Market Trends
The Carson Investment Research newsletter offers up-to-date market news, analysis and insights. Subscribe today!
"*" indicates required fields
Falling Valuations Don’t Mean Falling Markets
Michael Barczak, VP, Investment Due Diligence, looked at what all that earnings growth has done to valuations.
“The S&P 500 has produced positive returns year-to-date in 2026 (even accounting for the turbulence of the past few weeks), much of which has been driven by accelerating corporate earnings as mentioned above. This dynamic reflects improving underlying fundamentals, with resilient economic activity, strong corporate profitability, and continued investment in artificial intelligence and productivity-enhancing technologies supporting earnings growth.
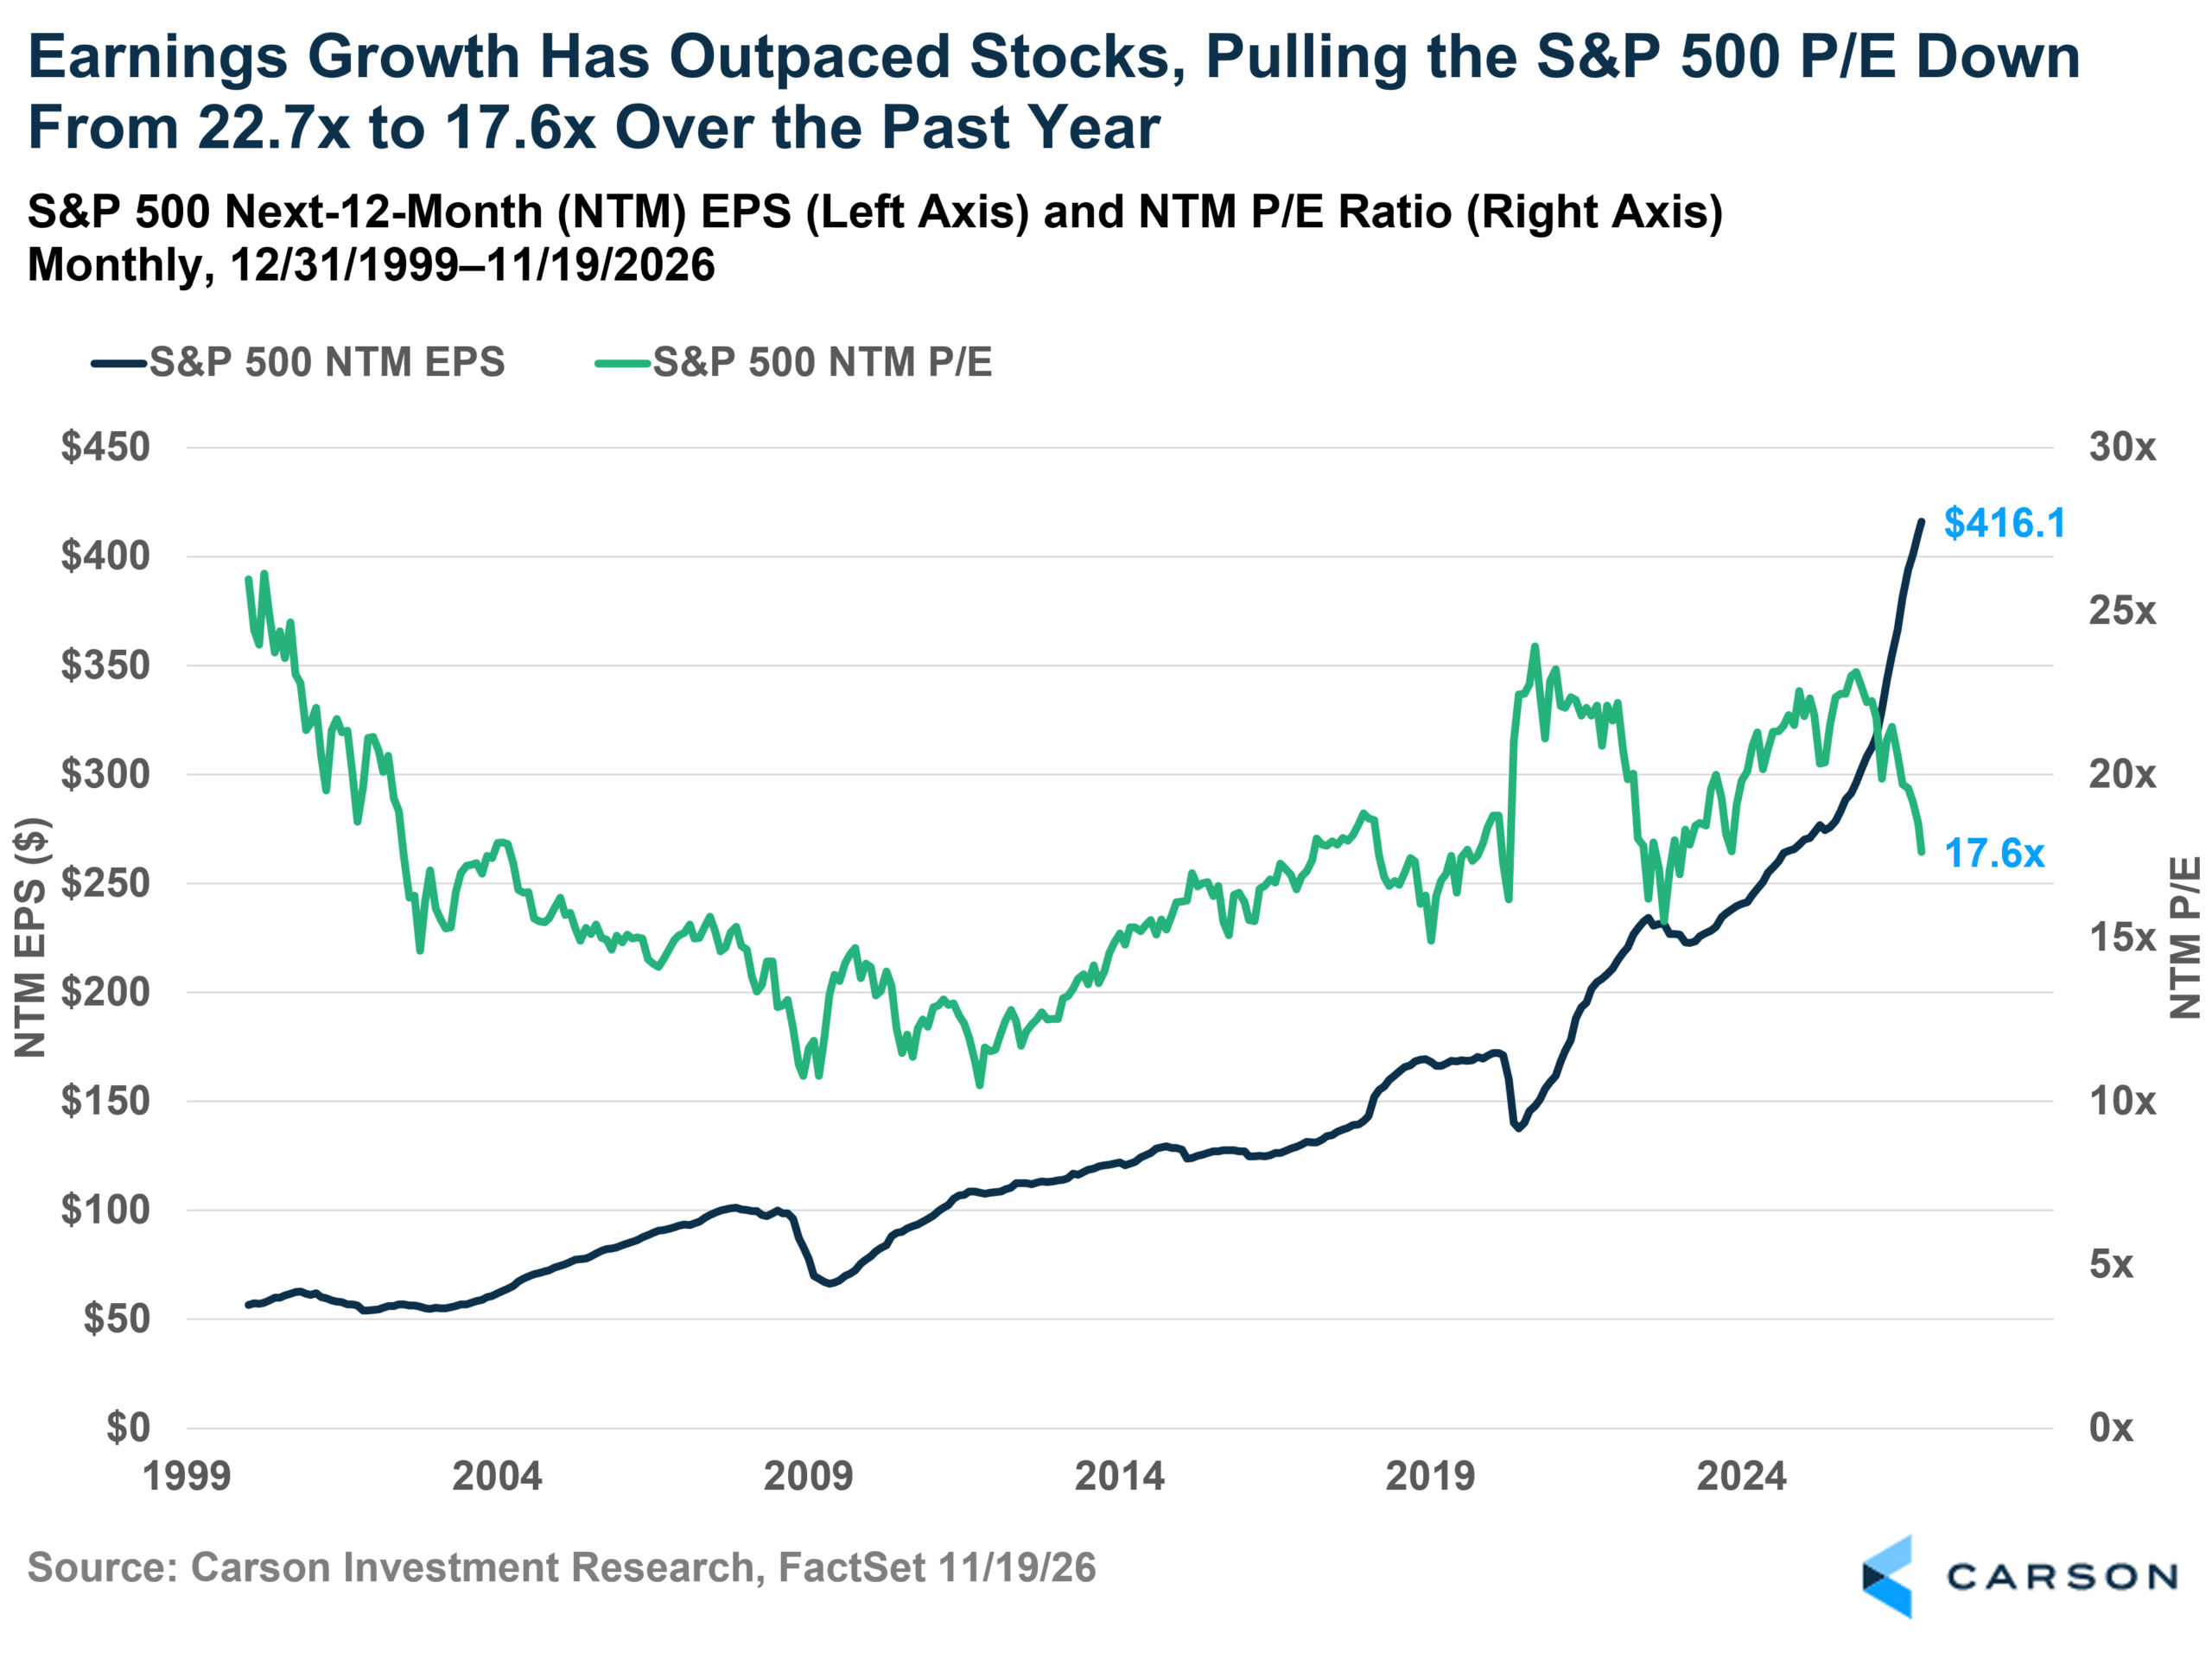
Despite strong market performance, P/E multiples have been declining as earnings growth has outpaced market gains. This phenomenon, often called earnings-driven multiple compression, suggests the market’s advance has been increasingly supported by fundamental earnings growth rather than investors simply paying higher prices for each dollar of earnings.
This time last year, markets were performing well, but valuations were nearing historic highs. Fast forward to today, and markets are higher than they were then and also look more reasonable from a valuation perspective, and for that I am thankful.”
The Consumer Is Solid
Ryan Detrick, Chief Market Strategist, went to the part of the economy that matters most for all of those earnings.
“There are lots of worries out there, but the strength of the consumer isn’t one of them.
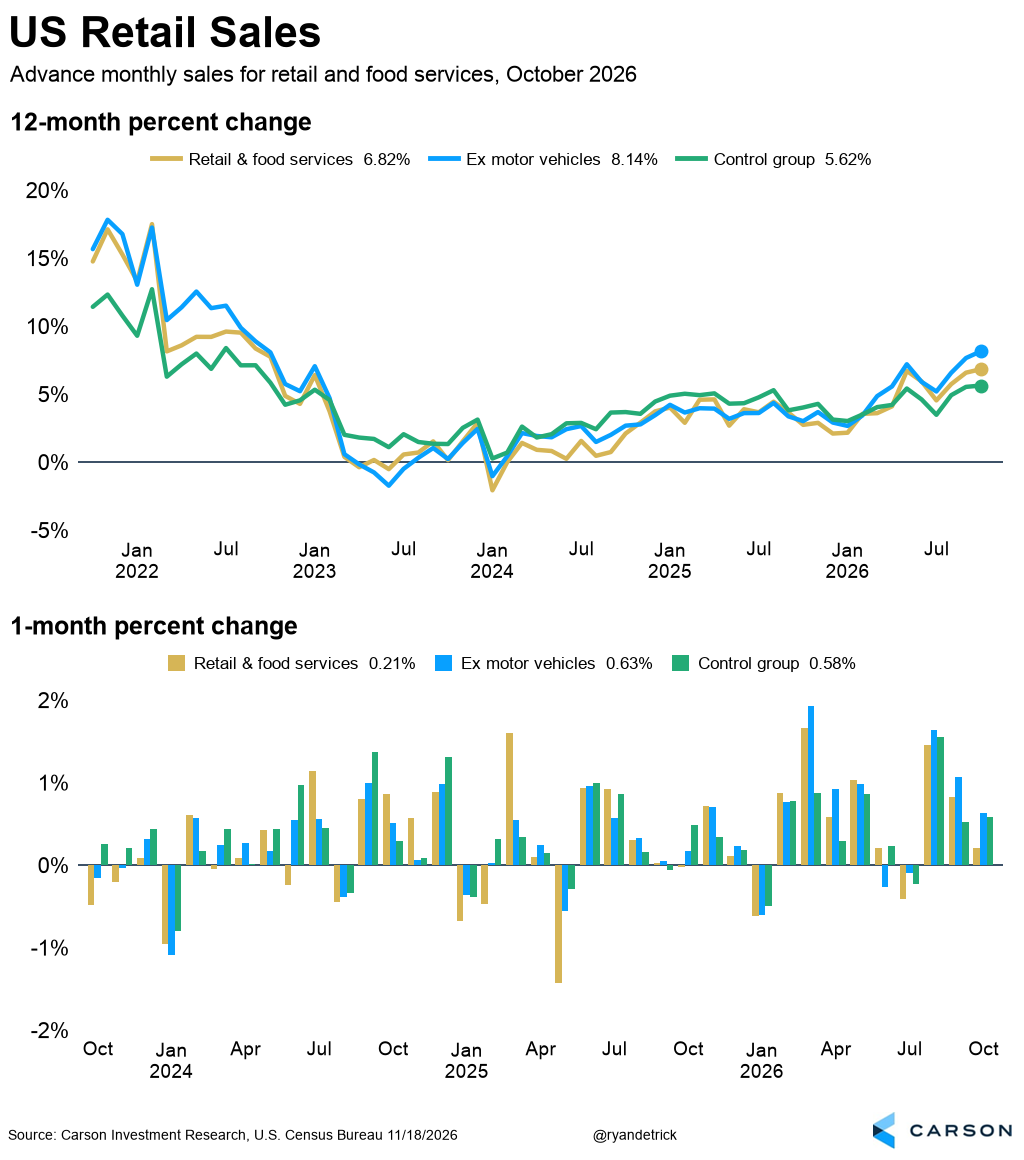
Consumer sentiment remains quite dour, but then we look at what consumers are actually doing: they continue to spend. Given consumer spending is a huge chunk of GDP, this is one more thing to be thankful for.
The recent retail sales data showed some bright spots, specifically the control group (which flows into GDP) came in at 0.6% versus the 0.4% that was expected, and the prior month was revised higher to 0.5% from 0.1%.”
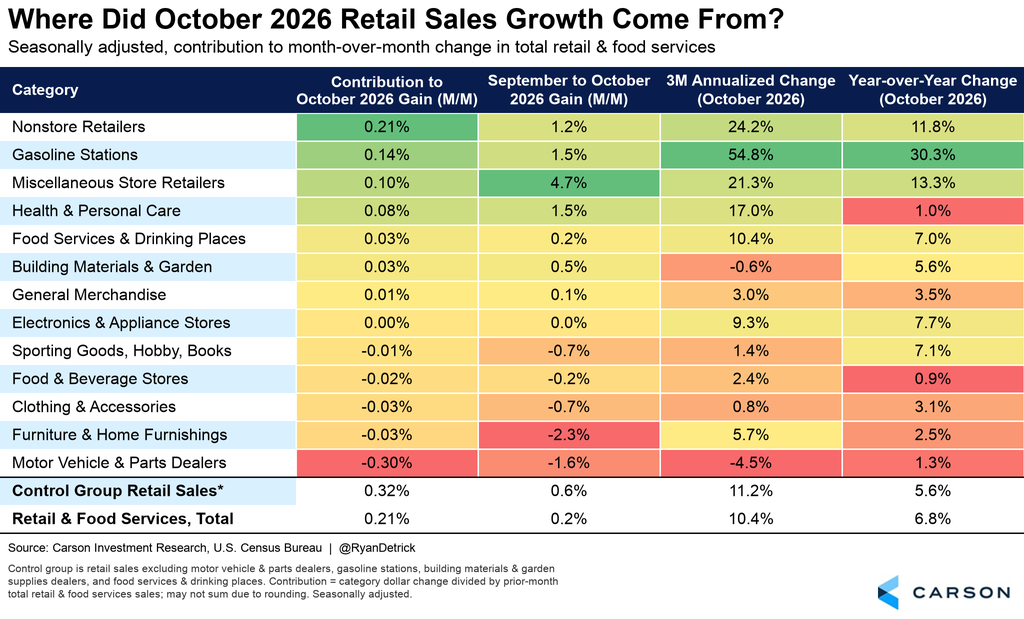
“Diving into the data and the 13 major subsectors, we see that food services and drinking places (think restaurants) were up more than 10% annualized the past three months. That is very impressive. If consumers were truly cracking, we don’t think they’d be spending like this at restaurants.”
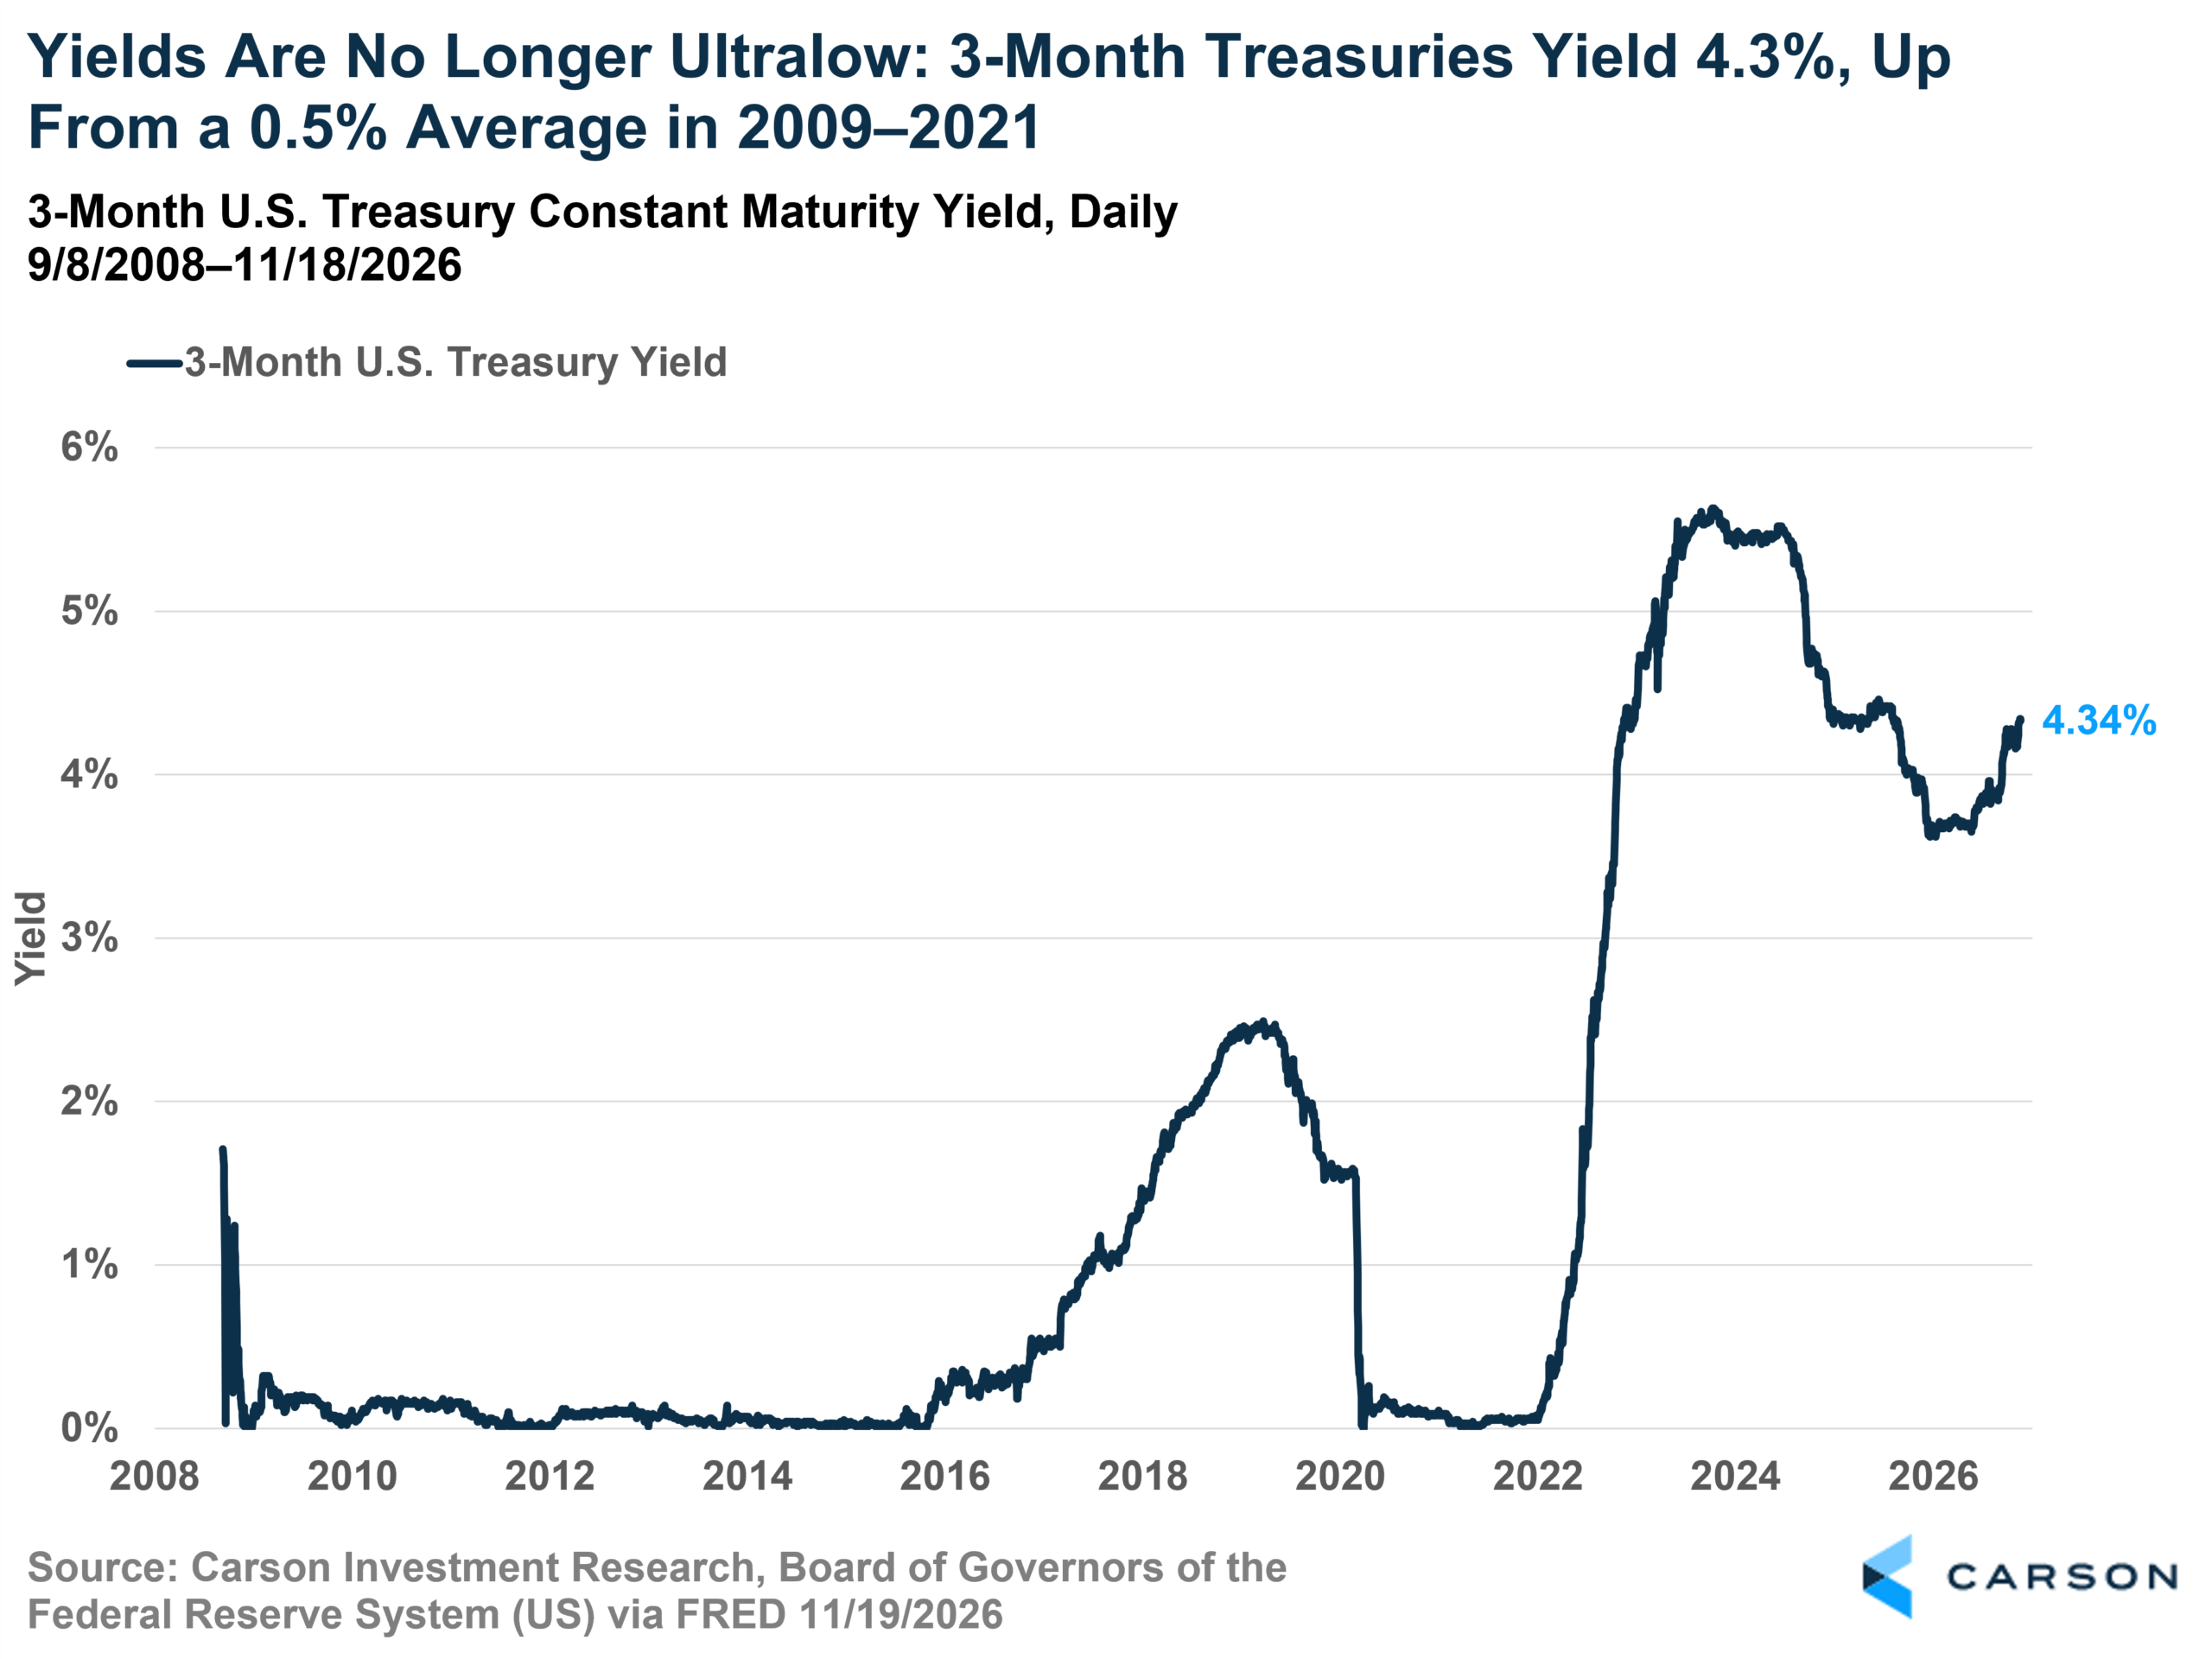
Yields Are No Longer Ultralow, and That’s Good for Investors
Barry Gilbert, VP, Asset Allocation Strategist, closed us out with a reminder that savers finally have something to be grateful for, too.
“From 2009 through 2021, interest rates were low. Borrowers were thrilled; savers were not. For most of that time, your savings account yielded hardly anything. Short-maturity Treasuries and CDs were scarcely better. Higher yields may not be good for the economy (although, from a long-term perspective, all yields have done is move back to a normal range), but they let investors get a higher return on ‘cash.’ Who doesn’t like a higher return for the same low risk? That’s something investors should be grateful for. Our one caution is that inflation eats away at returns, and that’s often why rates are higher. But let’s not quibble. It’s Thanksgiving.”
Wrapping It Up
Going into this, I figured we’d end up with a pile of AI charts. Instead, almost everyone picked something outside of it, whether that was health care, value stocks, the other 493, shoppers at restaurants, or the yield on a Treasury bill. I think that says something about where this market is right now. The AI trade gets most of the headlines, but plenty of good things happened this year that had nothing to do with it.
Thank you to everyone who shared a chart. From all of us at Carson, Happy Thanksgiving. For more blogs by the Carson Investment Research team, click here.
By Harry McDonald, Analyst, Investment Research
9249787.1. – 20NOV26A