“October: This is one of the peculiarly dangerous months to speculate in stocks. The others are July, January, September, April, November, May, March, June, December, August, and February.” Mark Twain
The bears had their shot last week, as Treasury yields soared and at a bad time too, as the third week of September is historically one of the worst weeks of the year. Unfortunately for the bears (and fortunately for the rest of us), they just couldn’t make headway. Yields may have moved to new highs, but stocks again shrugged off the worry and moved higher, with the tech-heavy Nasdaq hitting new highs and the S&P 500 less than one percent away from new highs.
In our 2026 Outlook: Ride the Wave, shared way back in January, we said we believed this would be a year of inflationary growth — with an economy that looks strong once you include inflation, robust earnings and profit margins, AI capex spending providing a boost, yields staying higher than most expected, and a labor market that keeps improving even as inflation stays sticky. Heading into the final quarter of the year, that call has generally been on target. Economic growth remains near trend, the unemployment rate has fallen despite modest job gains, and massive AI investment has helped fuel a historically large upside earnings surprise — which is what really matters to stocks. Speaking of the labor market, this Friday brings September’s nonfarm payrolls report, and we expect another decent print.
September Hasn’t Been So Bad and Welcome to the Best Month of a Midterm Year
With two trading days to go, the S&P 500 is exactly flat in the dreaded month of September. We heard all month how bad this month was going to be, but we pushed back against that narrative, and September has bucked the bearish sentiment, much like August did.
Stay on Top of Market Trends
The Carson Investment Research newsletter offers up-to-date market news, analysis and insights. Subscribe today!
"*" indicates required fields
We will be the first to admit you should never invest solely based on the calendar. Still, it’s important to understand history, and the good news for investors is some of the best times of the year to invest historically are near.
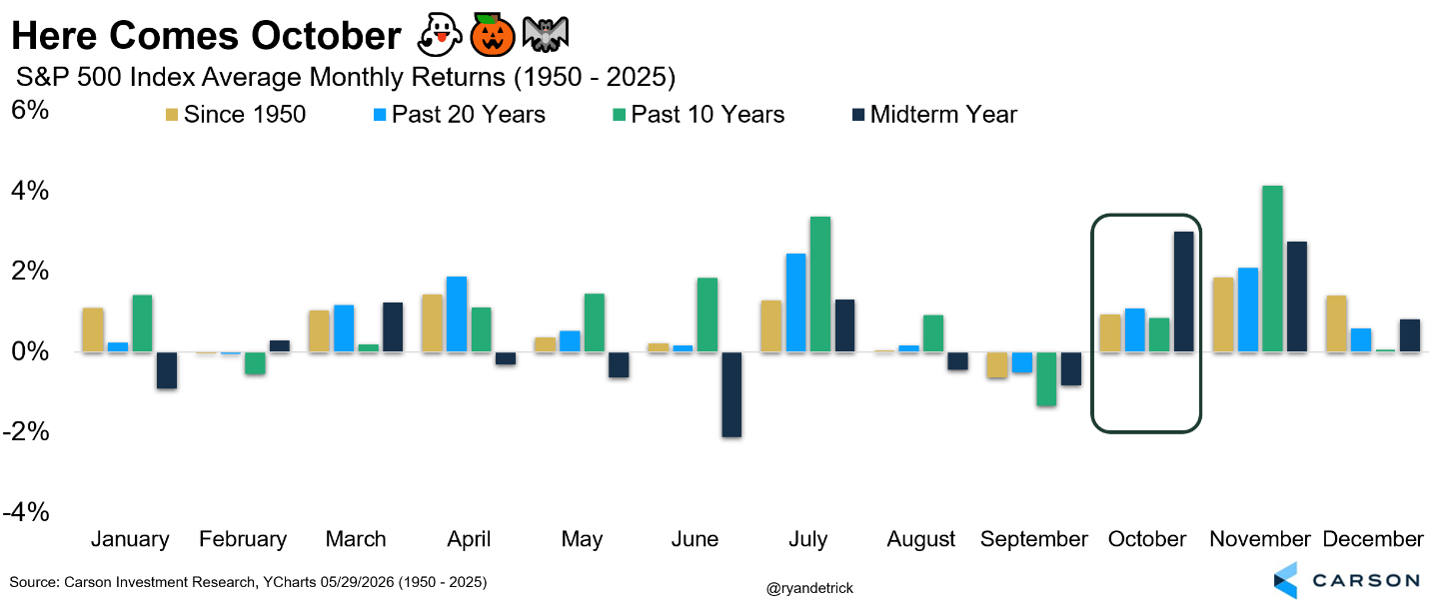
Yes, October is known for spectacular crashes — 1929, 1932, 1937, 1987, and 2008 were all down double digits. Here’s the thing, though: October might be very bad when it’s bad, but overall it ranks as the seventh-best month since 1950, the fifth-best over the past 20 years, and the eighth-best over the past 10 years. Not the best, but solid, and not so spooky overall.
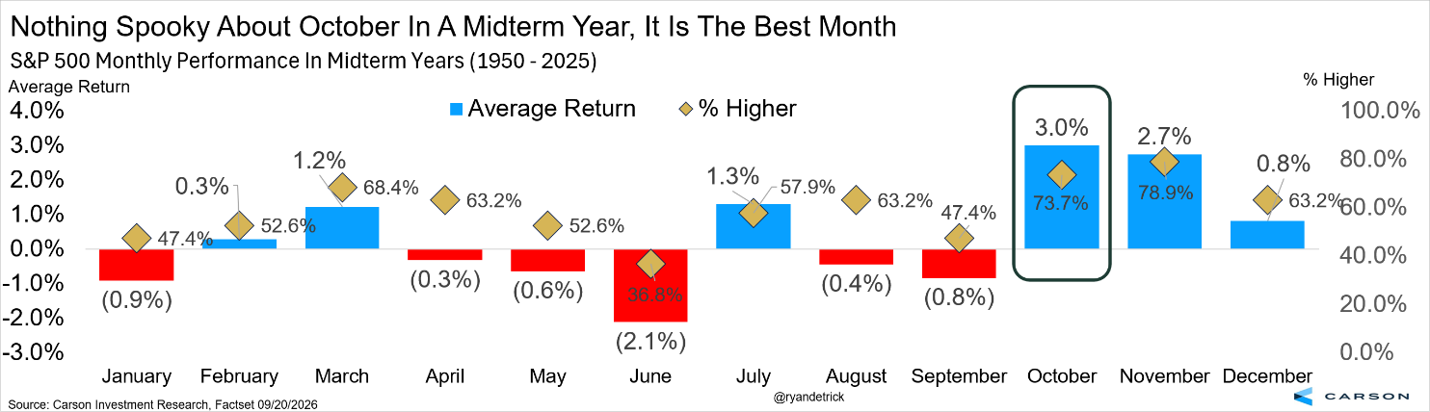
Where this month gets really interesting is in midterm election years. In a midterm year, October has been the best month of the year, up 3.0% on average and higher nearly 74% of the time. The second-best month is right behind it — November, up 2.7% on average and higher nearly 80% of the time. But there’s something for everyone here. In President Trump’s first midterm year, back in 2018, the S&P 500 fell nearly 7% in October, the only negative October in a midterm year over the past eight cycles.
We don’t suggest blindly investing based on this pattern, but we are expecting a strong fourth quarter to close out a nice year for investors, and this does little to change our view.
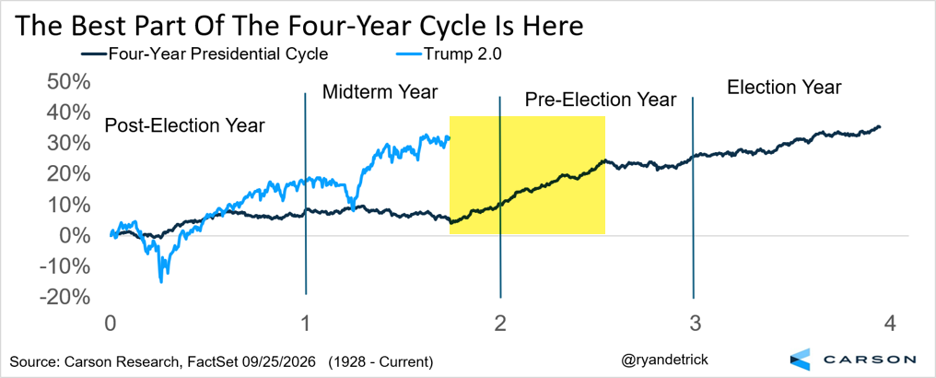
The Best Part of the Four-Year Presidential Cycle Is Now
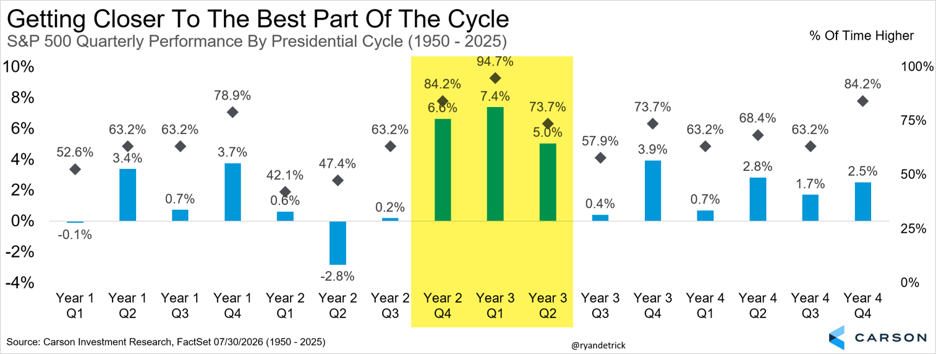
Taking this a step further, the fourth quarter of a midterm year and the first two quarters of a pre-election year (the next three quarters) are the three best quarters out of the entire 4-year presidential cycle. Stocks have done well under President Trump so far this midterm year relative to other midterm years, so some of the gains could be pre-loaded here. That’s always a possibility, but overall we remain optimistic this bull market is alive and well, and more gains are likely the rest of this year and into next.
Of course, the second quarter of a midterm year has historically been the worst quarter on average, and all it did this year was soar a record-breaking 15%. We use this as a guide, not gospel, as our friend Sam Stovall, chief investment strategist at CFRA, likes to say. As we noted in late March, when many others were cutting their targets and preparing for the worst, we said a rally was likely — which fortunately played out well.
Welcome to the Fourth Quarter
Here’s what I call one of those ‘it is what it is’ stats: the fourth quarter historically is the best quarter of the year, up more than 80% of the time and up 4.2% on average, twice the next best quarter.
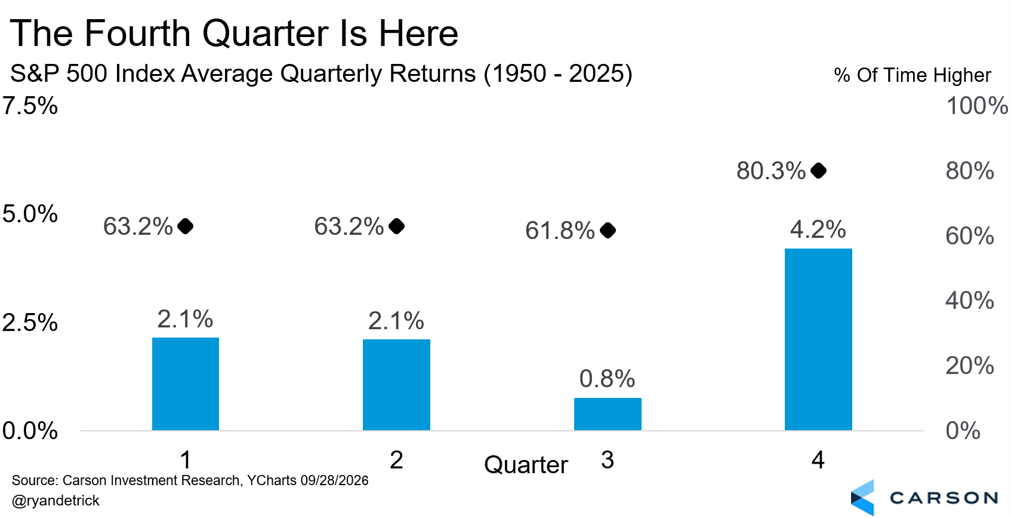
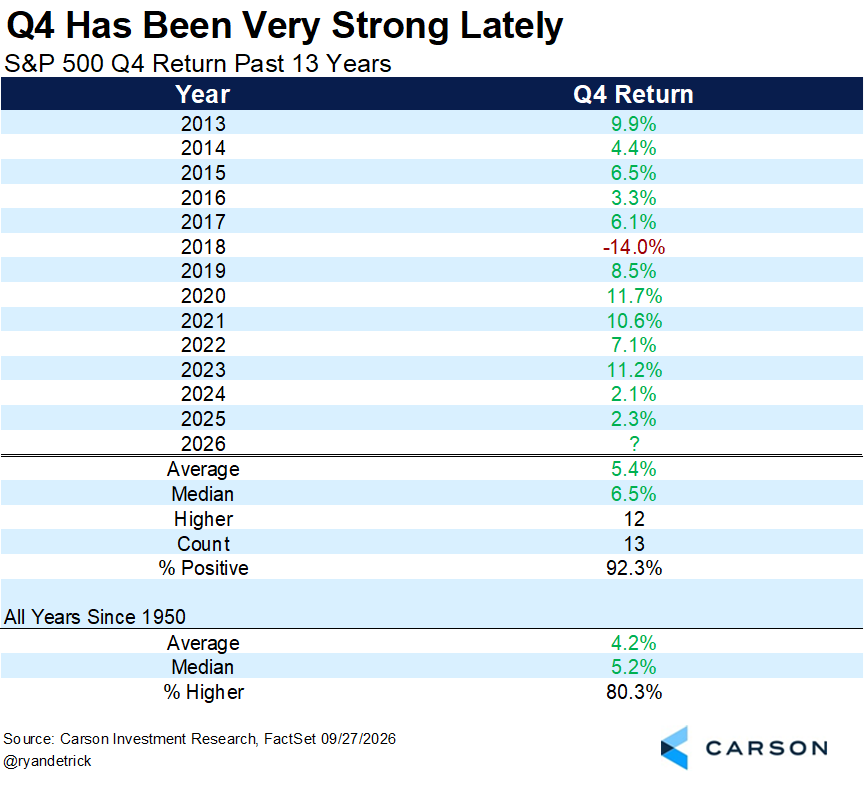
Lately, though, this quarter has been off the charts strong, higher than 12 of the past 13 years. But here’s the catch: the one time it was lower was a big drop in 2018, the last time President Trump was in office in a midterm year. Something for everyone here.
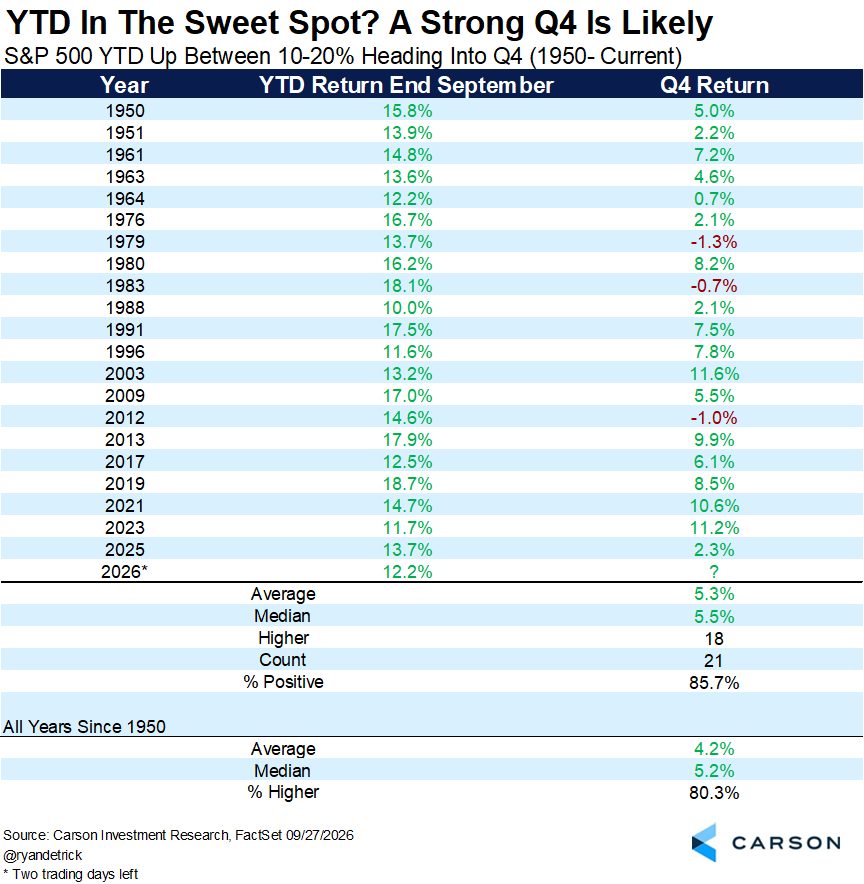
Lastly, another clue this year could end on a good note is that the year has been good so far, but not too good. We found 21 times the S&P 500 was up 10-20% going into the fourth quarter and those last three months were higher more than 85% of the time and up more than 5% on average, both better than an average year. Just like in golf when you hit the sweet spot and good things happen, this year has been in the sweet spot for returns and it could bode well for the bulls.
I had the honor of joining Morgan Brennan on CNBC Morning Bell yesterday to discuss many of these ideas, and you can watch the full panel discussion below. Thanks for reading!
For more content by Ryan Detrick, Chief Market Strategist, click here.
9151486.1. – 29SEPT26A