This week’s Big Tech earnings will likely feature investors scrutinizing the spending plans of cloud computing hyperscalers. As we approach this earnings season, the performance of these ‘Spenders of Capital’ has outpaced that of the ‘Receivers of Capital’ and may suggest that the perceived returns on investment are changing as well. Company commentary and investor analysis may focus on usage, utilization, and monetization to better gauge future spending plans.
Positive Correlation
ROCs and SOCs can live harmoniously. For the first years of this AI CapEx boom, the returns of stock prices between these two groups were positively correlated as the market capitalizations of each bucket increased in tandem. Sure, ROCs (comprising NVDA, AVGO, AMD, MU, and other semiconductors) vastly outperformed SOCs (MSFT, AMZN, GOOGL, META, and others in the cloud computing industry), as shown below. But the two groups moved largely in tandem.
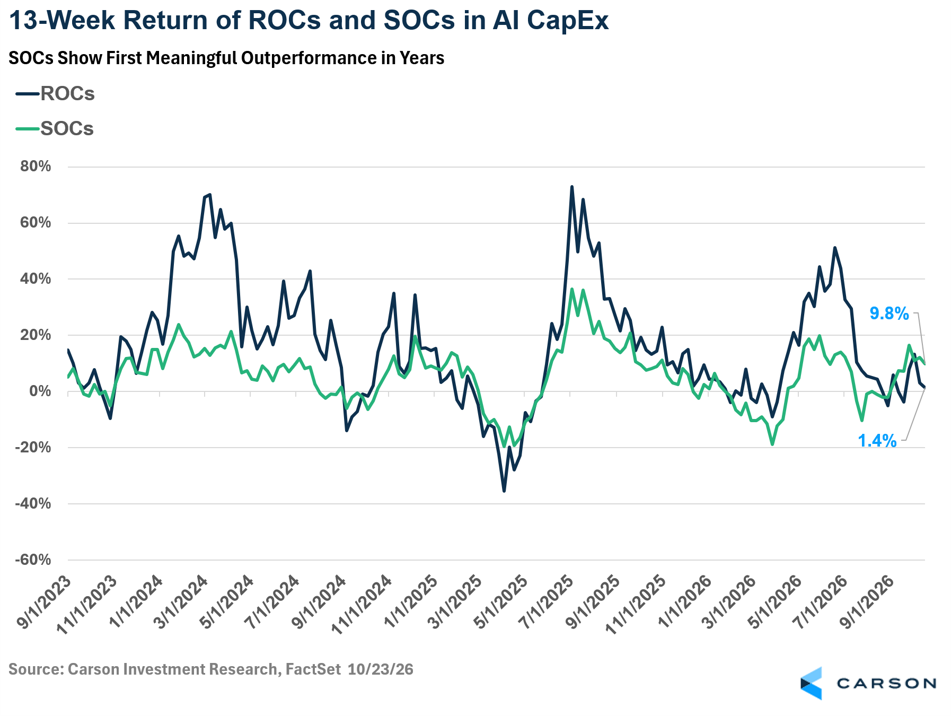
The logic of this mutual market cap increase was sound as well – the SOCs likely saw a positive return on investment in the products of the ROCs, and this could drive sustainable spending levels driven by increasing profitability.
Recent Divergence
Although the ROCs significantly outperformed from spring to summer, the SOCs have made a resurgence as of recent. Since last earnings season 13 weeks ago, the market cap of the SOCs has increased +9.8% whereas the market cap of the ROCs has only increased +1.4%.
Stay on Top of Market Trends
The Carson Investment Research newsletter offers up-to-date market news, analysis and insights. Subscribe today!
"*" indicates required fields
This +8.4% spread currently in favor of the SOCs is close to the +10.9% outperformance peak recorded for the group just a few weeks ago. Both of these data points highlight the drastic market shift since last earnings season – this most recent stretch of outperformance for the SOCs over the ROCs is the largest advantage the SOCs have had over the ROCs since we began tracking this dataset in 2023.
To me, this level of outperformance for the SOCs does potentially signal some shift in business conditions. The hyperscalers have been spending a tremendous amount of capital to purchase semiconductors, but they’ve also been vocal about getting more out of the semiconductors and data centers they’ve constructed. Perhaps market participants are correctly discerning among these technology companies that the SOCs are finding higher utilization or monetization out of their data centers and may outperform expectations in that sense.
A Look Ahead
A key comparison investors may be judging the SOCs by this earnings season is whether revenue growth (or growth expectations) is above that of capital expenditure growth (or CapEx growth expectations) as a signal of relative utilization improvement. Said differently, if SOCs are able to show investors that revenue growth can exceed expectations while capital spending forecasts are maintained, it may give investors a sense that these companies are better monetizing their pricey data center investments than previously expected. An outcome like this may give reassurance to market participants that the capital being spent is both finding adequate returns and is sustainable for at least the near future.
For more content by Blake Anderson, CFA®, Director, Portfolio Management, click here.
9201093.1. – 26OCT26A