Anthropic is set to price its initial public offering (“IPO”) deal terms Wednesday after the closing bell. Anthropic sits at the center of the ‘AI trade’ as its intelligence products have been at or near the ‘frontier’ for the past few years. With the company filing its IPO prospectus (also known as form ‘S-1’ with the SEC), key financial data became available to the investing public for the first time. The data received is clear: Anthropic appears to be well-capitalized, is cash-generating, and is rapidly growing revenue and profits.
Anthropic’s Rapid Growth
Anthropic’s revenue has been one of the most hotly debated financial metrics in markets this year, in my opinion. It matters so much to investors because it signals how economically viable these frontier-intelligence products may be and revenues can organically fund all the spending commitments Anthropic (and the broader AI industry) have made. As my colleague Sony Varghese, Chief Macro Strategist, detailed in the aforementioned blog, there’s been a lot of spending commitments made by Anthropic, other frontier intelligence labs, and the hyperscalers in the effort to build out the required infrastructure. To make good on these commitments, the labs need to find the capital either through profits or capital raising (with profits seen as the only sustainable way to meet these commitments).
Which makes Anthropic’s public release of their financials all that more important. Their filing showed that the company has rapidly become one of the largest software companies ever. As shown below, Anthropic’s latest quarterly revenue totaled nearly $17 billion. On an annual basis, revenue grew 1,126% from last year’s $1.38 billion result. This most recent revenue level has catapulted Anthropic to be above Salesforce’s revenue level in the latest quarter by a wide margin. In the past five quarters, Anthropic has grown from being smaller than all of Palantir, ServiceNow, and Salesforce to now receiving nearly as much revenue as those three combined ($16.96 billion versus $17.12 billion for the other three).
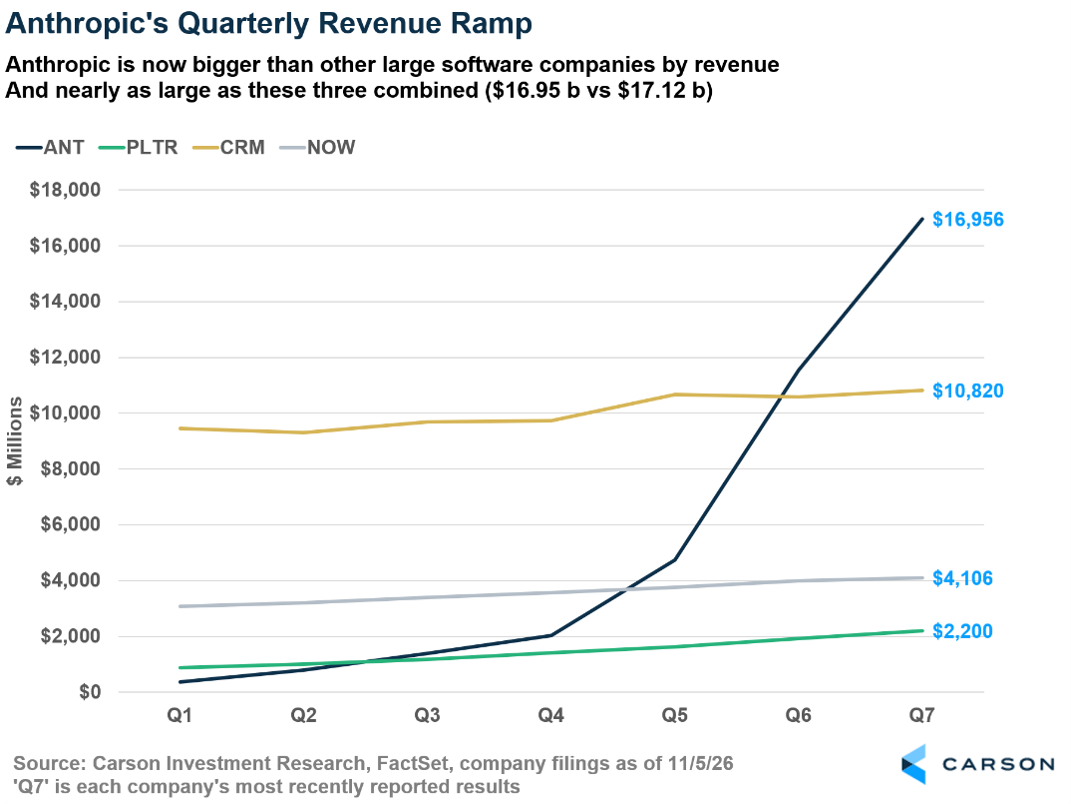
And it may be helpful to keep in mind that the total market cap for these other three large software firms totals $687 billion as of recent prices.
Anthropic’s booming revenue may send a signal to investors that their models are interesting and monetizable. But the more important detail may be the company’s booming profitability.
Anthropic’s Profitability
With Anthropic’s revenue growing gangbusters, investors may be wondering how much it costs. The company’s S-1 also revealed itemized income statement expenditures, although they classify expenses a bit differently than other technology companies. Rather than two separate line items for ‘Cost of Revenue’ (“CoR”) and ‘Research and Development’ (“R&D”) like many other technology firms disclose, Anthropic consolidates both expenditures into one ‘Technology and Infrastructure’ (“T&I”) line item.
Stay on Top of Market Trends
The Carson Investment Research newsletter offers up-to-date market news, analysis and insights. Subscribe today!
"*" indicates required fields
While consolidating these expenses into one line item does make like-for-like comparisons across technology firms tougher, investors may still find it valuable and worthwhile to assess Anthropic’s profitability. And those results show a ramp in profitability for Anthropic similar to its revenue growth, as shown below.
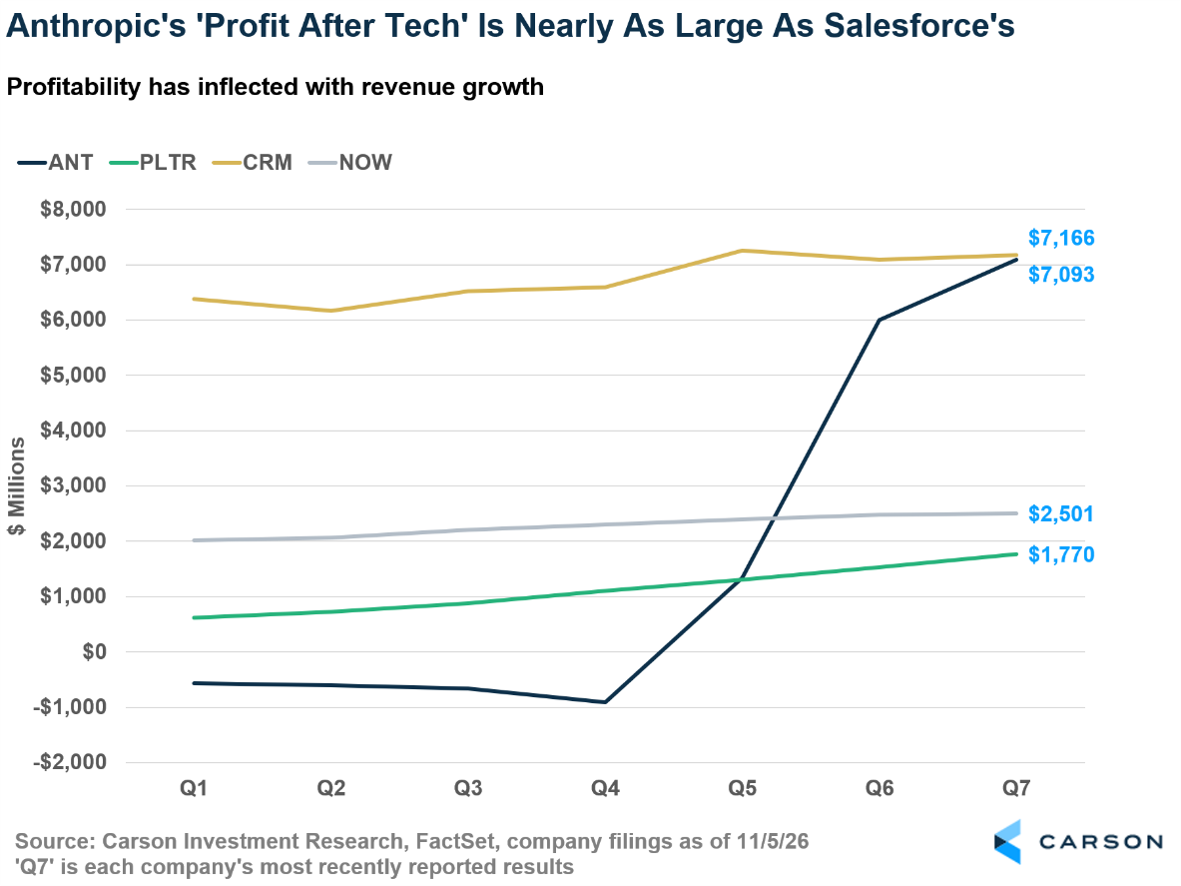
Not only are Anthropic’s revenues growing, but the company’s ‘profit after technology spending’ is booming as well. This quarter’s result shows a profitability level nearly equivalent to that of Salesforce. And what investors may cheer the most about these results is the flip from negative to positive in the previous year. While skeptics of Anthropic may have correctly said a year ago that the company was unsustainably burning cash by running a large operating loss, the company has shown investors it can scale profits with revenue.
Anthropic’s Valuation
The company’s financials reveal that the underlying economics of selling frontier intelligence products are robust and are increasingly in favor of the company as profitability is inflecting. In my opinion, this can allow investors to ‘dream the dream of growth,’ especially with the company on track to raise a hoard of cash in this week’s IPO.
It’s a fair question then to ask ‘is Anthropic overvalued’ at its potential IPO price. While I can’t answer which way it will go, and the deal price may finalize above or below some recent projections, we can at least compare valuations across the tech landscape.
If we assume Anthropic will IPO at a $1.5 trillion fully diluted market cap, it will trade at about 22x market cap to annualized trailing quarterly sales. This valuation multiple lands smack in the middle compared to other large technology firms, as shown below.
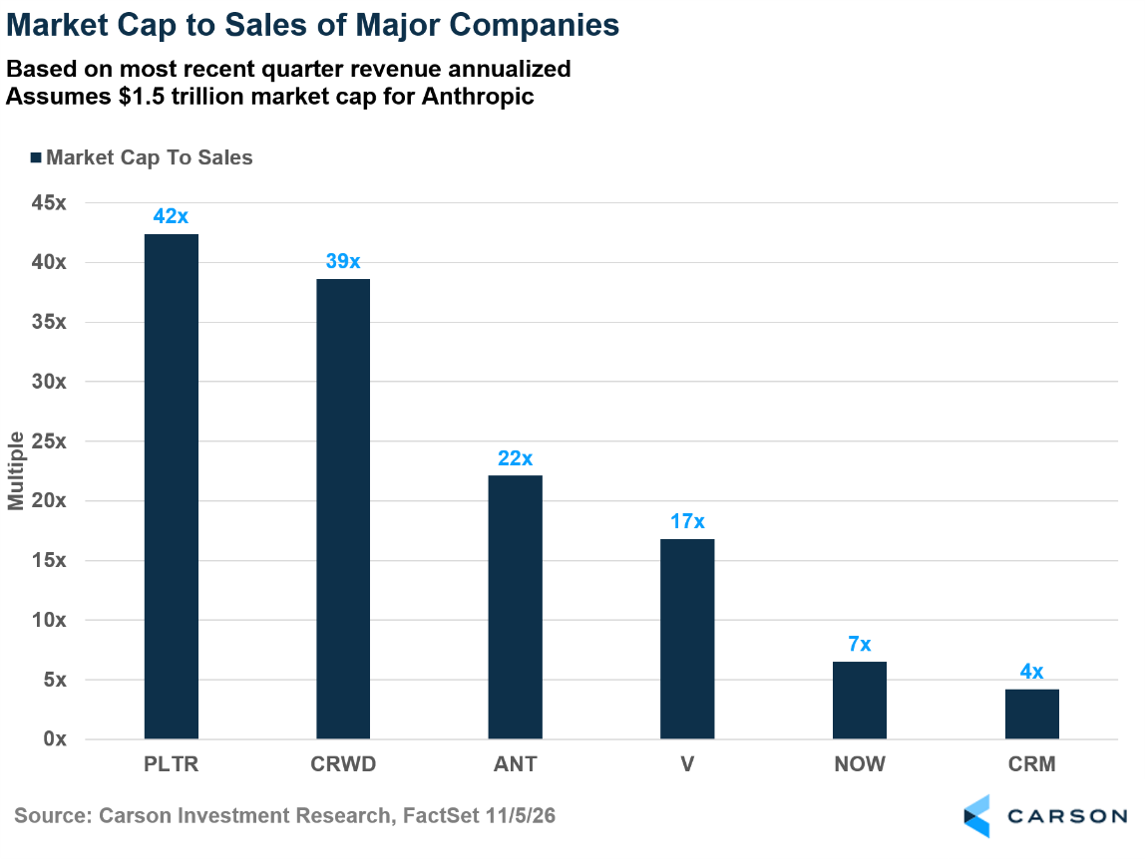
If we look at more expensive technology companies – which the market is deeming ‘AI winners’ in my opinion – such as Palantir and CrowdStrike, those two trade at roughly 40x market cap to last quarter’s revenue annualized, as shown above. On the other hand, companies that the market is deeming as ‘AI Disrupted’, such as ServiceNow and Salesforce, trade at roughly 5x market cap to last quarter’s sales annualized. Anthropic’s 22x multiple lands in the middle between ‘AI Winner’ and ‘AI Disrupted.’
Said differently, Anthropic’s valuation based on the data known seems neither demanding nor discounted. In fact, Anthropic’s multiple is comparable to Visa’s 17x multiple. Perhaps investors are viewing Anthropic as a highly durable platform upon which modern AI systems are built and run, much like how Visa is perceived as a highly durable payment platform upon which much of the global economy runs.
Anthropic’s IPO this week is one of the most anticipated public offerings in history. And the company’s financials appear to largely live up to the hype. Amid doubts about liquidity and profitability, Anthropic has raised money at opportunistic times to build one of the strongest balance sheets in the world and has proven that its intelligence products can deliver impressive economic results to the company. Their product roadmap has delivered one of the most impressive revenue growth stories in history, and investors now appear to be pricing the company as a highly durable platform. If investors are looking for proof that AI’s growth and potential is bigger than one man in the wake of Huang’s fallout, they might first look to Anthropic’s IPO this week.
Cover image courtesy of Beinsure https://beinsure.com/news/anthropic-ipo-date-nasdaq-listing/
For more content by Blake Anderson, CFA®, Director, Portfolio Management, click here.